
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mixed on Wednesday as higher oil prices and rising Treasury yields intensified inflation concerns, while a rebound in semiconductor shares supported the Nasdaq. The S&P 500 fell 0.3% and the Dow dropped 577 points, whereas the Nasdaq 100 gained 0.3%. Financial and payment stocks weakened alongside major AI hyperscalers amid concerns over elevated data center spending, while Broadcom and Nvidia advanced on stronger demand prospects and new commercial developments.
Market Movers
Among the top-performing stocks of the session Nuvve Holding Corp, Inc. surged 63.58%, while Tvardi Therapeutics, Inc. rallied 61.29%. On the losing side, Sadot Group Inc. fell 49.23%, while. Julong Holding Limited declined 29.17%, making them the weakest performers during the trading day.
Commodities Update
WTI crude held near USD 73.5 per barrel and Brent near USD 78.3 on Thursday after surging 4.4% and 5.2%, respectively, in the previous session, as renewed US-Iran hostilities revived concerns over Middle East supply and traffic through the Strait of Hormuz. Although vessel activity through the key route has slowed and remains concentrated along Iran-approved channels, the actual impact on oil flows is still unclear, as substantial shipments continued before the ceasefire and some volumes appeared in tracking data only after a delay.
Gold rose above USD 4,100 an ounce and silver approached USD 59 on Thursday as the oil rally lost momentum, although both metals remained pressured by inflation concerns linked to renewed US-Iran hostilities and potential energy supply disruptions through the Strait of Hormuz. The US conducted strikes on Iran for a second consecutive day, prompting retaliatory attacks on American bases, while President Trump declared the ceasefire over and warned of further action. Meanwhile, Federal Reserve minutes showed limited support for a rate increase but heightened concern over inflation, with markets still expecting at least one hike by the end of 2026.
Macro Updates
The US dollar index held near 101 and remained on course for a weekly gain as renewed US-Iran hostilities boosted safe-haven demand and pushed oil prices higher, reinforcing concerns that inflation could keep interest rates elevated. Although the Federal Reserve’s June minutes showed limited support for another rate increase, officials remained increasingly concerned about inflation, while markets continued to expect at least one hike by the end of 2026 ahead of weekly jobless claims and existing home sales data.
Bonds Commentary
The US 10-year Treasury yield held near a seven-week high of 4.58% on Thursday as renewed US-Iran hostilities lifted oil prices and intensified inflation concerns, reinforcing expectations for at least one Federal Reserve rate hike by the end of 2026. Although the Fed’s June minutes showed limited support for higher rates, officials remained increasingly concerned about inflation, while investors awaited weekly jobless claims and existing home sales data for further guidance on the policy outlook.
Futures Update
US equity futures were largely flat on Thursday as macroeconomic uncertainty, higher Treasury yields and renewed volatility in semiconductor stocks kept investors cautious. Micron and Sandisk rose about 3% premarket as enthusiasm around memory-chip demand strengthened ahead of SK Hynix’s heavily oversubscribed ADR launch, while traditional sectors remained under pressure after outperforming technology shares earlier in July. Meanwhile, slowing tanker traffic in the Persian Gulf raised concerns about energy-driven inflation, and Meta fell 2% following reports that it plans to begin producing its own AI chip by September.
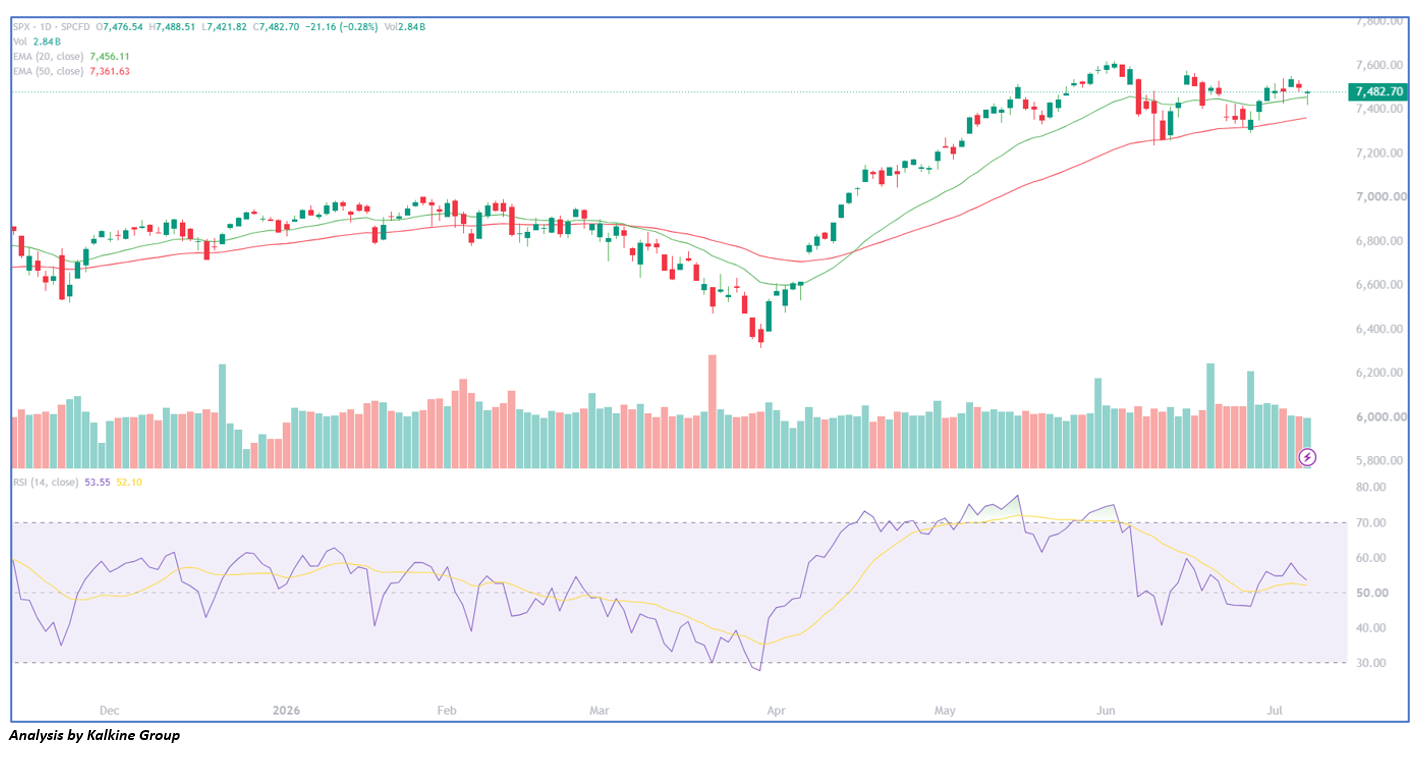
After coming under significant selling pressure early in Wednesday's session, U.S. stocks staged a steady recovery through the day, with the major averages rebounding from their intraday lows and the Nasdaq finishing in positive territory. From a technical perspective, the S&P 500 remains in a healthy short-term uptrend, holding comfortably above its 20-day EMA (7,456) and 50-day EMA (7,362), reinforcing the strength of the broader bullish trend. The index continues to consolidate following its recent advance, while the RSI near 54 reflects neutral momentum, leaving room for further gains. As long as the S&P 500 remains above the 20-day EMA, the bullish outlook stays intact, with a breakout above the current consolidation range likely to pave the way for another test of recent highs.

 Nov 15, 2026
 Please wait processing your request...