
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indices closed lower on Tuesday as tighter financial conditions, rising bond yields and Inflation concerns linked to the US-Iran conflict weighed on sentiment. The S&P 500 fell 0.7%, the Dow declined 419 points and the Nasdaq 100 dropped 1.3%, led by losses in technology and asset-management stocks.
Market Movers
Among the top-performing stocks of the session Sono Group N.V. surged 77.43%, while Fly-E Group, Inc. rallied 61.76%. On the losing side, Alumis Inc, Inc. fell 56.58%, while Picard Medical, Inc. declined 54.37%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices remained near six-week highs on Wednesday, with WTI around USD 90 per barrel and Brent near USD 94, supported by renewed US strikes on Iran and escalating threats that raised concerns over Supply disruptions through the Strait of Hormuz. However, fears were partly tempered by reports that 17 million barrels of oil transited the strait on Monday, the highest daily Volume since the conflict began.
Gold traded near USD 4,300 per ounce and silver around USD 64 on Wednesday, hovering near three-week and two-week lows, respectively, as rising Global Bond yields, higher oil prices and mounting inflation concerns strengthened expectations of tighter monetary policy. Hawkish comments from Fed Chair Kevin Warsh pushed the probability of a rate hike this month to around 70%, with investors awaiting the ADP employment report and nonfarm payrolls for further policy signals.
Macro Updates
US Mortgage Applications Edge Higher Despite Elevated Rates
US mortgage applications rose 0.8% in the week ended August 28, 2026, recovering from two consecutive weekly declines. Purchase applications increased 2.2%, while refinancing Demand fell 1.1%. Meanwhile, the average 30-year fixed mortgage rate edged up to 6.79% from 6.78%, as rising Treasury yields, Middle East-related inflation concerns and expectations of a September Federal Reserve rate hike kept borrowing costs elevated.
US Dollar Climbs on Rate-Hike Expectations
The dollar index rose above 99.7 on Wednesday, reaching a nearly three-week high as surging oil prices heightened inflation concerns and strengthened expectations of a Federal Reserve rate hike. Hawkish comments from Fed officials pushed the probability of an increase this month to around 70%, while investors awaited the ADP employment report and nonfarm payrolls for further policy signals.
US Crude Inventories Decline as Production Rises
US Crude Oil inventories fell by 2.6 million barrels in the week ended August 28, reversing the previous week’s 4.2 million-barrel increase. The Strategic Petroleum Reserve declined by another 3.1 million barrels to 286.6 million, while domestic production rose to 13.843 million barrels per day. Gasoline inventories increased by 300,000 barrels, distillate stocks fell by the same amount and Cushing inventories rose by 200,000 barrels.
Bonds Commentary
The US 10-year Treasury Yield climbed above 4.8%, approaching its highest level since October 2023, as rising oil prices fuelled inflation concerns and increased expectations of a near-term Federal Reserve rate hike. Markets assigned around a 70% probability to a hike this month, with upcoming US employment data expected to provide further policy signals.
Futures Update
US Equity futures were subdued on Wednesday as tight financial conditions, rising bond yields and inflation risks stemming from the US-Iran conflict weighed on sentiment. S&P 500 and Dow futures were flat, while Nasdaq 100 futures declined 0.7%, led by weakness in technology stocks. Dell surged nearly 10% following upbeat Earnings and higher guidance, while Nvidia remained flat amid reports of a potential USD 14 billion Acquisition of Hugging Face.
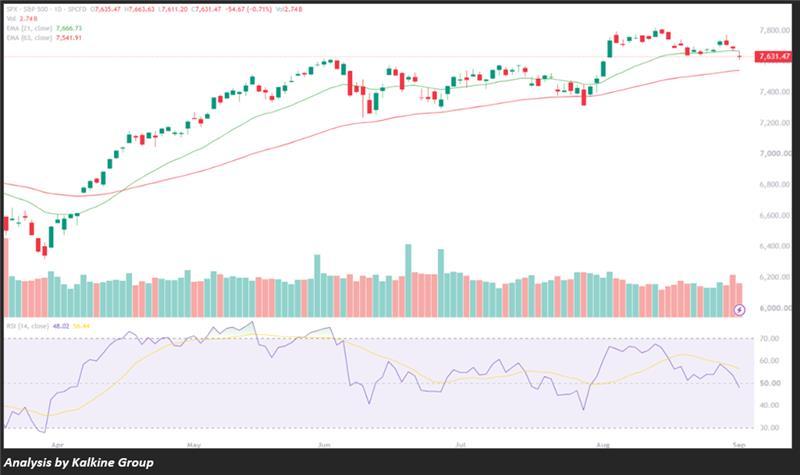
After moving moderately lower over the previous two sessions, stocks experienced a more pronounced decline during Tuesday’s trading session. The major averages fell sharply, with the tech-heavy Nasdaq leading the losses. Although the indices recovered somewhat from their session lows, they still closed firmly in negative territory. The S&P 500 is currently trading near 7,631 after facing resistance at higher levels. The index has moved below its 21-day EMA of 7,666.73, indicating near-term weakness, while it continues to hold above the 50-day EMA at 7,541.91, keeping the broader trend relatively constructive. The RSI (14) stands at 48.02, reflecting neutral momentum. Immediate support is placed around 7,610–7,600, followed by stronger support near 7,540, while resistance is seen around 7,665–7,700. A decisive break below 7,600 could trigger further downside, whereas a sustained move above 7,665 could revive buying interest. Overall, the intraday outlook remains neutral to slightly bearish, with the index likely to remain under pressure unless it regains the near-term resistance zone.

 Nov 09, 2026
 Please wait processing your request...