
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity

Index Update
US stocks fell sharply on Friday as disappointing technology Earnings raised concerns about AI Demand and the returns on rising Capital spending. The Nasdaq dropped 3.5%, the S&P 500 fell 1.8% and the Dow lost 572 points. Intel plunged 28.6% on weak guidance, AMD fell 11% and Amazon slipped 1.4% after its Q3 results missed expectations and it announced higher spending. ExxonMobil and Chevron bucked the decline, gaining 2.2% and 1.7%, respectively, after beating Q3 forecasts. All three indices ended the week lower. For the month, the Nasdaq fell 6.6% and the S&P 500 declined 0.9%, while the Dow gained 1.7%.
Market Movers
Among the top-performing stocks of the session ChowChow Cloud International Holdings Limited. surged 106.57%, while Grid Dynamics Holdings, Inc. rallied 40.78%. On the losing side, ProMIS Neurosciences Inc. fell 70.13%, while Apollo Commercial Real Estate Finance, Inc. declined 63.88%, making them the weakest performers during the trading day.
Commodities Update
Brent and WTI crude each fell 4.5% on Monday, approaching USD 108 and USD 99 per barrel, respectively, as Qatar-mediated talks between the US and Iran eased fears of further oil Supply disruptions. President Trump signalled a preference for diplomacy, while Iranian officials said an agreement remained possible if commitments were honoured. The risk of escalation persisted, with reports that both sides were preparing for possible military action after the November 3 US midterm elections. Separately, OPEC+ kept its production targets unchanged through December.
Gold rose above USD 3,900 per ounce and silver approached USD 50 per ounce on Monday, with both metals rebounding modestly from around one-year lows. Diplomatic efforts to avert renewed US military action against Iran helped push oil prices lower, easing concerns about energy-driven Inflation and further Federal Reserve rate increases. Both metals had come under pressure the previous week as investors sold holdings to cover losses during an AI-related Equity selloff. Markets still priced in roughly a 75% chance of a December rate hike ahead of this week’s US jobs report.
Macro Updates
US Dollar index Slips to 101.7 Ahead of October Jobs Report
The US Dollar Index fell to around 101.7 on Monday, extending recent losses as investors awaited the October jobs report, ISM Manufacturing and services surveys, and remarks from Federal Reserve officials. The Fed held rates steady last week, but markets still priced in roughly a 75% chance of a December rate hike. Oil prices retreated on reports of continued diplomatic efforts ahead of the US midterm elections, while easing pressure on AI stocks reduced demand for safe-haven assets.
Bonds Commentary
The US 10-year Treasury Yield held near 4.93% on Monday, close to a seven-week low, as investors awaited the October jobs report, ISM manufacturing and services surveys, and remarks from Fed officials. The Fed held rates steady last week, but markets priced in roughly a 75% chance of a December rate hike. Oil prices fell on reports that President Trump favoured giving diplomacy more time ahead of the midterm elections, while easing pressure on AI stocks reduced demand for safe-haven assets.
Futures Update
US stock futures edged higher on Monday ahead of the midterm elections, the October jobs report and earnings from Apple, Palantir and AMD. Dow futures rose 0.3%, while S&P 500 and Nasdaq 100 futures each gained about 0.4%. Investors also awaited ISM manufacturing and services data and remarks from Federal Reserve officials for clues on interest rates. The gains followed a week in which disappointing technology earnings renewed concerns about the AI trade. The Nasdaq Composite fell 2% last week, while the Dow lost 0.85% and the S&P 500 declined 0.57%.
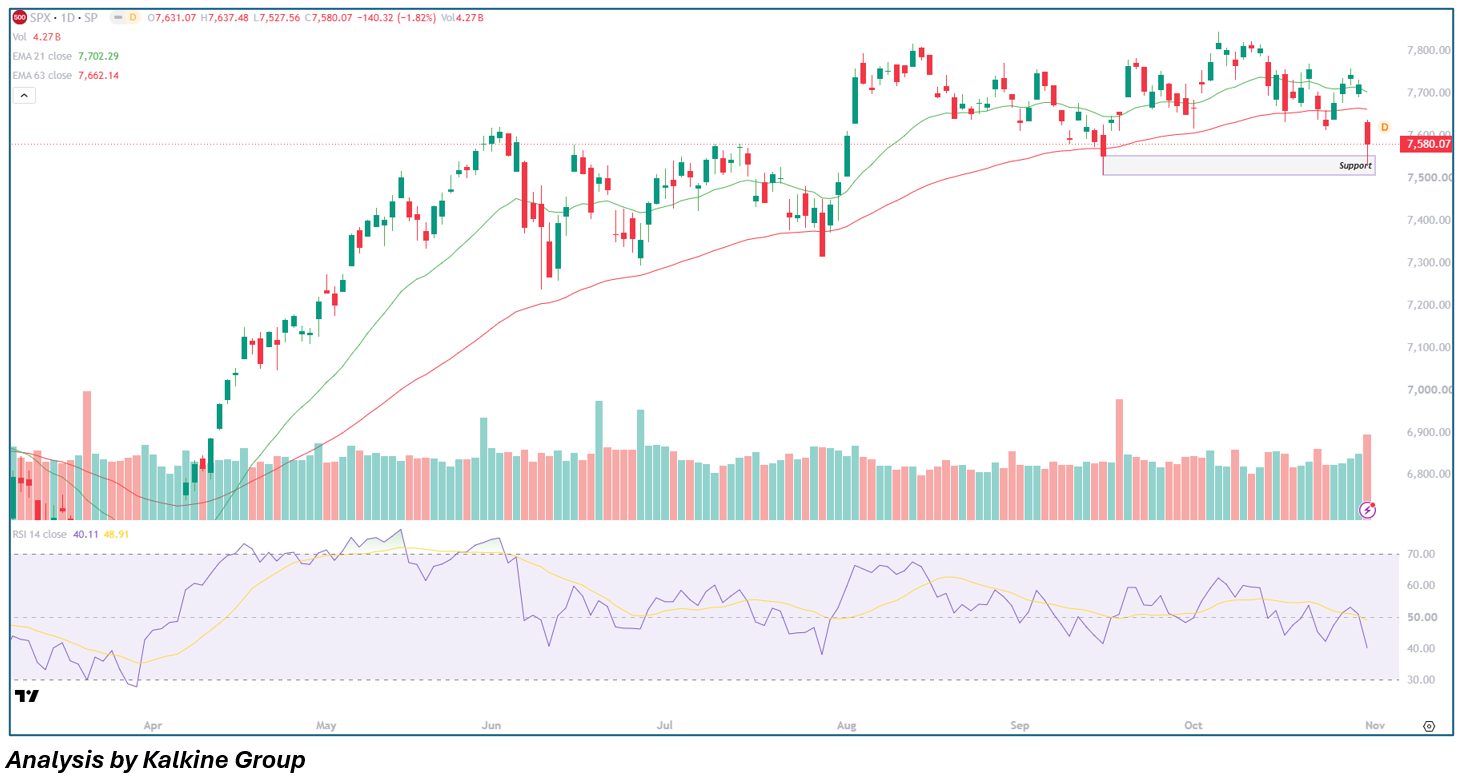
U.S. stocks tumbled on Friday, led by steep losses in tech-heavy benchmarks as heavy institutional selling pushed indices lower despite a late-day recovery attempt. The S&P 500 Index (SPX) plunged -1.82% (-140.32 pts) to 7,580.07 on an elevated Volume spike of 4.27B shares, slicing below both its 21-day EMA (7,702.29) and 63-day EMA (7,662.14). With the 14-day RSI breaking down to 40.11, holding above the 7,527.56 session low and pivotal 7,520–7,580 support shelf is crucial to avoid an extension toward the 7,450–7,480 August base, while any relief attempts face immediate resistance at 7,637–7,662.

 Oct 30, 2026
 Please wait processing your request...