
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks fell on Thursday, with the S&P 500 down 0.3%, the Nasdaq losing 1.4% and the Dow shedding 135 points as disappointing Earnings revived concerns over the AI trade. Alphabet plunged 12.6% after missing earnings and Revenue estimates, while Amazon and Intel declined ahead of results. Caterpillar fell 9.4% on a modest growth outlook, while Eli Lilly and Merck gained after raising guidance. Meanwhile, US Q3 GDP grew a stronger-than-expected 3.4%, and September PCE Inflation accelerated.
Market Movers
Among the top-performing stocks of the session Katapult Holdings, Inc. surged 37.58%, while ADT Inc. rallied 33.20%. On the losing side, Iovance Biotherapeutics, Inc. fell 35.45%, while Solowin Holdings. declined 34.86%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose above USD 103 per barrel to six-week highs on Friday, while Brent surpassed USD 112, nearing four-year highs, amid fears of renewed US strikes on Iran. Both benchmarks have gained over 10% in October as regional clashes and tanker attacks heightened Supply concerns around the Strait of Hormuz. However, efforts to restart US–Iran peace talks and a recovery in regional crude exports toward prewar levels provided some counterbalance.
Gold fell below USD 4,000 per ounce on Friday, while silver slipped below USD 51 to its lowest since November 2025, as persistent US inflation and robust economic growth strengthened expectations of a Federal Reserve rate hike. September annual PCE inflation reached 3.6%, while third-quarter GDP grew 3.4%, exceeding forecasts. Despite the Fed holding rates steady, markets priced in roughly a 75% probability of a December hike. Gold and silver were on track for October losses of nearly 4% and 15%, respectively, marking potential second consecutive monthly declines.
Macro Updates
US Dollar Weakens as Treasury Yields Retreat
The US dollar index fell toward 101.5 on Friday, marking its third consecutive decline as a global technology and AI stock selloff boosted Demand for Government Bonds and lowered Treasury yields. Disappointing earnings from Alphabet, Amazon and Intel heightened concerns over AI spending. Meanwhile, September’s 0.5% monthly increase in PCE prices reinforced inflation concerns, with markets pricing in roughly a 75% probability of a December Fed rate hike.
US Mortgage Rates Ease for Second Consecutive Week
The US 30-year fixed mortgage rate fell to 7.24% as of October 29, 2026, from 7.32% the previous week, tracking declining Treasury yields. Despite its second consecutive weekly drop, the rate remained above 6.17% a year earlier. The 15-year fixed mortgage rate also declined to 6.60% from 6.68%.
Bonds Commentary
The US 10-year Treasury Yield fell toward 4.9%, a seven-week low, as disappointing technology earnings and a global tech and AI stock selloff drove demand for government bonds. The decline came despite stronger-than-expected Q3 GDP growth of 3.4% and a 0.5% monthly rise in September PCE prices, which reinforced inflation concerns. Markets continued to price in roughly a 75% probability of a December Fed rate hike.
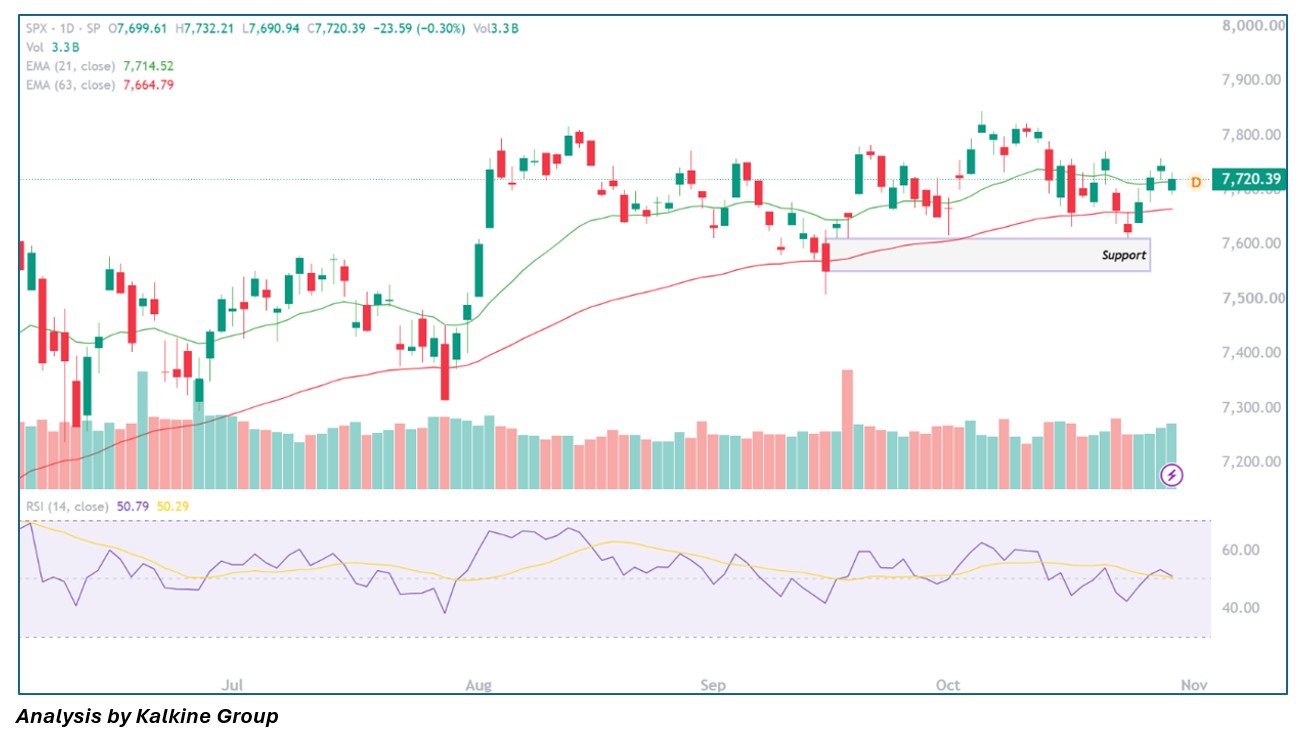
U.S. equities pulled back on Thursday as resurfacing AI valuation concerns drove a sharp drop in the tech-heavy Nasdaq. In tandem, the S&P 500 Index (SPX) eased -0.30% (-23.59 pts) to 7,720.39, consolidating between dynamic support at the rising 63-day EMA (7,664.79) and overhead resistance at the descending 21-day EMA (7,714.52). With the 14-day RSI holding near equilibrium at 50.79, holding above the 7,690.94 session low keeps a retest of 7,732.21 and the 7,780–7,800 range high in play, while a breakdown below the low threatens a drop to the 7,664.79 Moving Average floor.

 Oct 29, 2026
 Please wait processing your request...