
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mixed on Wednesday as rebounding oil prices and elevated Treasury yields offset softer-than-expected Inflation data. The S&P 500 fell 0.2% and the Dow lost 444 points, while the Nasdaq gained 0.2%. Financials and industrials weakened, while AI and semiconductor stocks advanced ahead of Micron’s earnings. August core PCE inflation of 0.2% eased expectations of an October Fed hike. For September, the S&P 500 declined 0.4%, the Nasdaq 100 gained 3.2%, and the Dow shed 2,280 points.
Market Movers
Among the top-performing stocks of the session GOWell Energy Technology. surged 75.70%, while Creative Media. rallied 52.60%. On the losing side, Liquidia Corporation. fell 57.19%, while Columbus Acquisition Corp declined 30.14%, making them the weakest performers during the trading day.
Commodities Update
Crude oil climbed above USD 91 a barrel, while Brent approached USD 100 on Thursday, as reports of PetroChina suspending October gasoline and jet-fuel exports to preserve domestic inventories heightened Supply concerns. Saudi Arabia’s resumption of tanker loadings at Yanbu and recovering Middle Eastern shipments eased fears of crude shortages, although refined fuel supplies remained tight. Uncertainty over US–Iran negotiations and ongoing conflicts continued to weigh on the supply outlook.
Gold climbed toward USD 4,200 an ounce, while silver rebounded above USD 61 on Thursday, as softer-than-expected US inflation data lowered expectations of an October Fed rate hike. August headline and core PCE rose 0.3% and 0.2%, respectively, reducing October hike odds to 38% from 51%. Improving Middle Eastern energy flows eased oil prices, although stalled US–Iran negotiations and persistent inflation concerns kept Treasury yields elevated, with markets still pricing in a 97% probability of a December rate increase.
Macro Updates
US Job Cuts Ease in September as Employers Remain Cautious
US employers announced 43,281 job cuts in September 2026, down from 52,881 in August and 54,064 a year earlier, marking the lowest September total since 2022. Technology led with 10,799 cuts, followed by food and services. Third-quarter layoffs fell 43% from Q2 to 129,591, while cuts through September declined 39% year over year to 573,195. Despite easing layoffs, employers remained cautious amid elevated energy costs, geopolitical uncertainty and potential increases in borrowing and healthcare costs.
Dollar Climbs to Highest Level Since April 2025
The dollar index rose for a fourth consecutive session to above 101.8, extending September’s 2% gain as persistent inflation, resilient US economic activity and hawkish Fed comments supported expectations of further tightening. Markets fully priced in another 25-basis-point hike this year and nearly four additional increases by end-2027, although October hike odds eased to around 37% from 70% last week. The dollar strengthened against the yen, pound and euro.
Bonds Commentary
US Treasury yields rose on Thursday as expectations of further Fed tightening, persistent inflation and fiscal concerns extended the bond sell-off. The 10-year yield reached 5.33% and the 30-year climbed to around 5.67%, both their highest levels since 2002, while the 2-year yield rose to 4.91%. Higher oil prices, unresolved Middle East tensions and resilient economic data reinforced expectations of another rate hike this year.
Futures Update
US stock futures rose on Thursday as investors began Q4, with S&P 500 futures gaining 0.4%, Nasdaq 100 advancing 0.9% and Dow futures adding nearly 80 points. AI optimism and Micron’s upbeat outlook supported sentiment despite higher Treasury yields and oil prices. Alphabet climbed 2.2% following its latest AI model rollout, while most megacap technology stocks advanced. Apple fell 0.4%, and Nike edged lower ahead of earnings.
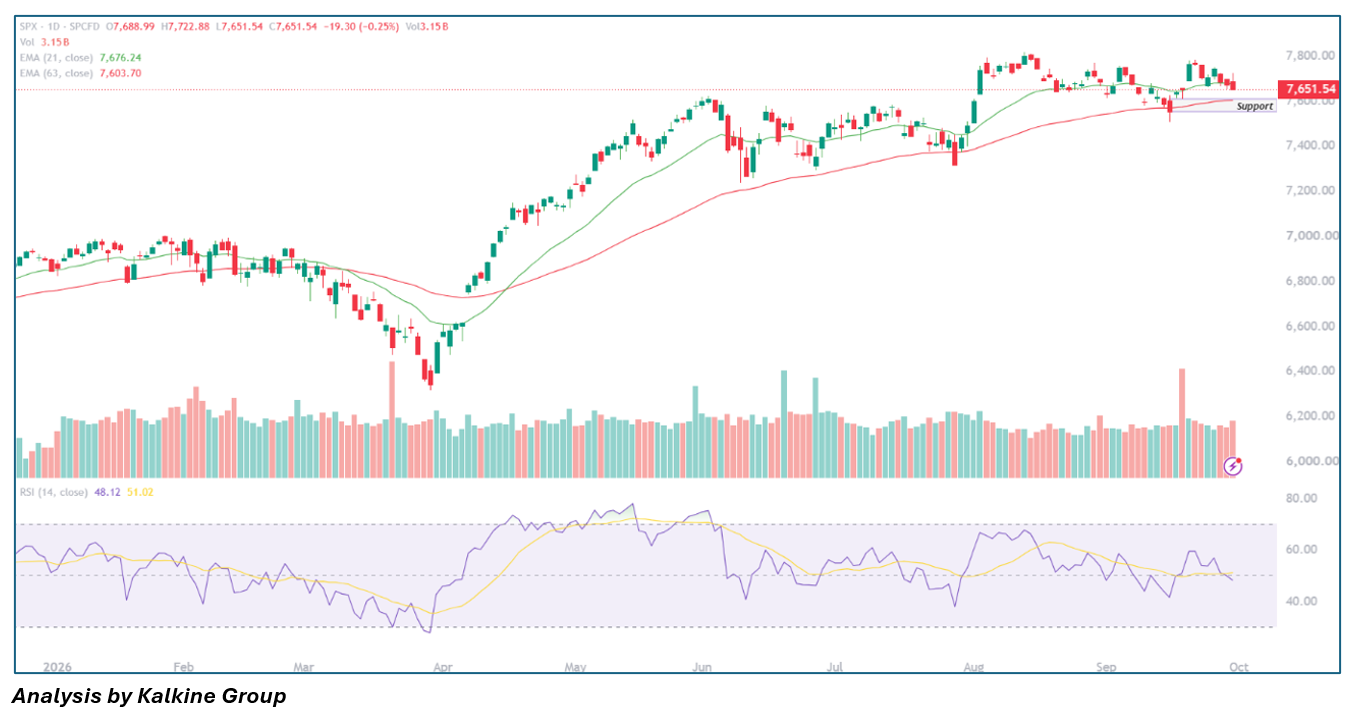
Stocks moved mostly higher in early trading on Wednesday but surrendered those gains as the session wore on. The major averages retreated well off their highs, with the Dow and S&P 500 slipping into negative territory and both finishing at their lows of the day. Technically, the S&P 500 closed at 7,651.54 (-0.25%), at the session low after failing to hold gains near 7,723. That leaves it below its 21-day EMA (7,676) but above its 63-day EMA (7,604), while the RSI at 48 has dipped under its signal line, pointing to a cautiously bearish, range-bound bias. Immediate resistance sits at 7,676, followed by the 7,690 to 7,723 zone, with support at 7,604 and then the 7,560 to 7,600 band. If the index can't reclaim 7,676 early in the next session, a drift toward 7,604 becomes the likelier path, whereas holding above it would put 7,720 back in play. A decisive break below 7,560 would expose the early-September low near 7,510, though with the index confined to a range of roughly 7,560 to 7,800 since August, mean-reverting moves look more probable than a breakout.

 Nov 09, 2026
 Please wait processing your request...