
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
US stocks rebounded on Friday, ending four consecutive losing sessions as oil prices stabilised and Treasury yields eased. The S&P 500 and Nasdaq 100 gained 0.9%, while the Dow added 509 points, supported by technology and financial stocks. Dell surged 11.9% following an RBC Outperform initiation, while Oracle fell 1.8% despite strong results. However, all three major indices finished lower for the week as persistent Inflation and expectations of a Fed rate hike weighed on sentiment.
Market Movers
Among the top-performing stocks of the session MKDWELL Tech Inc. surged 51.96%, while ACV Auctions Inc. rallied 44.18%. On the losing side, U Power Limited. fell 32.84%, while CVD Equipment Corporation declined 25.36%, making them the weakest performers during the trading day.
Commodities Update
Crude oil climbed above USD 103 per barrel and Brent reached USD 109 on Monday, marking four-month highs as the Iran war intensified Middle Eastern Supply disruptions. Attacks forced Saudi Arabia to shut its East-West pipeline, cutting off a key alternative export route to the Red Sea, while Iran postponed talks with GCC countries on restoring supplies. Prolonged tanker disruptions and production cuts, alongside dwindling Chinese stockpiles, increased Import Demand and near-record-low US strategic reserves, further supported prices.
Gold hovered near USD 4,300 an ounce and silver remained below USD 64 on Monday after three consecutive weekly declines, pressured by surging oil prices and expectations of tighter Federal Reserve policy. Middle Eastern supply disruptions heightened inflation concerns, with markets pricing in an 86% chance of a 25-basis-point rate hike on Wednesday. US annual inflation held at 3.4% in August, while monthly CPI rose 0.4%, producer prices accelerated and resilient employment reinforced the hawkish interest-rate outlook.
Macro Updates
The US Budget Deficit narrowed to USD 167 billion in August 2026 from USD 345 billion a year earlier, well below the USD 404 billion forecast, as spending fell to USD 527 billion and receipts rose to USD 360 billion. Social Security and net interest were the largest expenditures, while income taxes led revenues. The cumulative fiscal-year deficit reached USD 1.966 trillion through August.
Bonds Commentary
The US 10-year Treasury Yield hovered near 4.96% on Monday, close to its highest level since October 2023, as markets priced in an 86% chance of a 25-basis-point Fed rate hike on Wednesday and another increase later this year. Stronger-than-expected Core Inflation and surging oil prices reinforced rate expectations, while a Treasury buyback of USD 5.2 billion, below the USD 6 billion maximum, disappointed investors.
Futures Update
US Equity futures fell on Monday, with the S&P 500 down 0.6%, Nasdaq 100 declining 1.5% and Dow slipping 0.2%, as calls for slower AI development heightened concerns over technology spending. Chipmakers and AI infrastructure stocks led losses, with several falling 5–8% and Nvidia dropping 2.5%. Elevated Treasury yields and rising energy prices amid prolonged Middle Eastern supply disruptions added pressure ahead of the Federal Reserve’s policy decision.
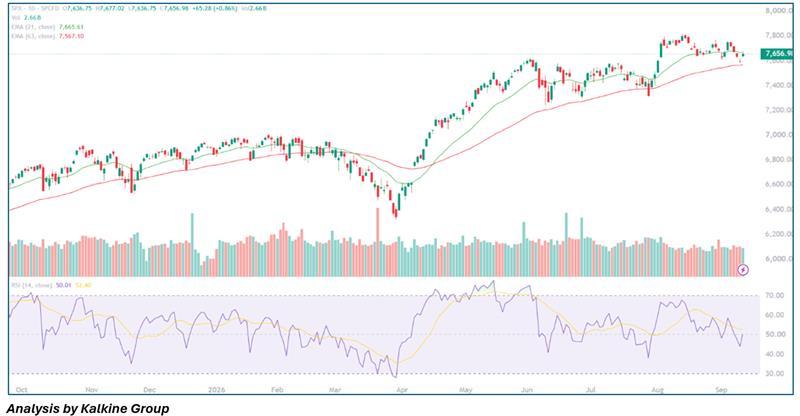
After opening sharply higher early in Friday’s session, stocks maintained a strong upward trajectory throughout the day. All major averages posted solid gains, recovering from the weakness seen during the previous several sessions. Although the indices retreated modestly from their intraday highs toward the close, they remained firmly in positive territory. The S&P 500 (SPX) is trading near 7,656.98, up 0.86%, with the near-term technical setup remaining neutral to slightly bearish. The index is currently below its 21-day EMA at 7,665.61, suggesting some near-term resistance, while it continues to hold above the 63-day EMA at 7,567.10, preserving the broader underlying support structure. Momentum remains subdued, with the 14-day RSI at 50.01, below its 52.40 signal line, reflecting limited bullish conviction. Immediate resistance is located around 7,665–7,700, followed by 7,750–7,780, while key support lies near 7,600–7,570, with stronger support around 7,500. A sustained breakout above 7,700 could reinforce the bullish momentum and push the index toward 7,750–7,780. Conversely, a break below 7,600 could trigger renewed selling pressure toward 7,570–7,500. Overall, the index is likely to remain range-bound with a cautious bearish bias until buyers decisively reclaim the 21-day EMA

 Nov 09, 2026

 Please wait processing your request...