
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
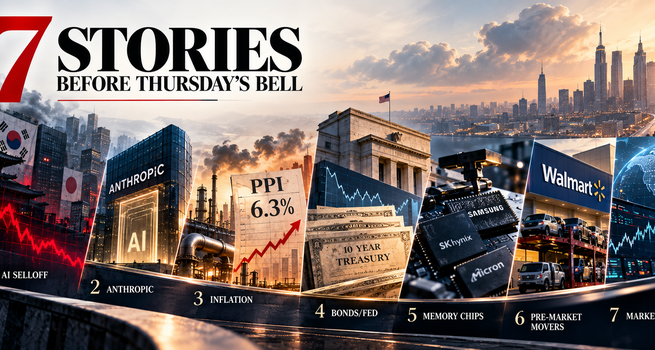
S&P 500 and Nasdaq-100 futures fell as worries about tech companies' borrowing for the AI build-out hit Asia, where South Korea's Kospi plunged 7.57% and Japan's Nikkei 225 fell 4.9%. Producer prices jumped 6.3% on the year, Treasury yields dropped as investors fled to bonds, and Anthropic told investors its Revenue reached $16.8 billion.
1. AI SELLOFF: Kospi Plunges 7.6% and the Nikkei Falls 4.9% on AI Borrowing Fears as CoreWeave Slides for a Second Day
South Korea's Kospi plunged 7.57% to 5,554.22, dragged by SK hynix and Samsung Electronics, which fell more than 11% and nearly 10%. Japan's Nikkei 225 lost 4.9%, SoftBank fell by a similar amount to Samsung and China's CSI 300 lost 1.23%. In US pre-market trading, CoreWeave (NASDAQ:CRWV) fell 5% to 6% after tumbling more than 15% on Wednesday, as yields on its bonds hit 15%. Its CEO said markets were acting "irrationally" and that its Backlog justifies its debt. Micron (NASDAQ:MU) fell 4%, AMD (NASDAQ:AMD) nearly 3%, Sandisk (NASDAQ:SNDK) 4% and SK hynix's US-listed shares 7%. The Nasdaq Composite had its biggest one-day decline since July 23 on Wednesday.
- The sell-off has moved from stock valuations to the cost of funding AI infrastructure.
- Risk note: Nasdaq-100 futures are on track for a sixth decline in 7 sessions, and a Fed hike this year would add stress for Data Center operators carrying record debt.
2. ANTHROPIC: Tells Prospective Investors Q3 Revenue Rose 45% to $16.8 Billion and That It Was Profitable on an Adjusted Basis
Anthropic told prospective investors in San Francisco on Wednesday that third-quarter revenue rose to $16.8 billion from $11.6 billion in the second quarter and $4.7 billion in the first. It said it was profitable on an adjusted basis in the quarter. It is targeting a valuation of more than $2 trillion in an IPO expected in November, likely after the Nov. 3 midterms. Analysts who met its executives estimate its annual revenue run rate could reach $110 billion by year-end. Last year its revenue rose twelvefold to nearly $4.6 billion while it lost more than $8 billion on an operating basis, and it has committed at least $518 billion over a decade for cloud services, computing and infrastructure. Some traders worry its revenue is not growing fast enough to justify chipmakers' gains.
- The IPO is expected to precede OpenAI's listing, making it an early test of investor appetite for loss-making AI developers.
- Risk note: the profit claim is on an adjusted basis, and the $518 billion of commitments keep the focus on whether revenue can outrun costs.
3. INFLATION: Producer Prices Jump 1.3% in September for a 6.3% Annual Rise as Retail Sales Beat at 0.8%
The producer price index rose 1.3% in September, its sharpest monthly gain since March 2022, against 0.5% to 0.6% expected. The annual rate reached 6.3% against 5.5% expected, the highest since December 2022. Core PPI, which excludes food and energy, rose 0.7% against 0.3% expected, its biggest gain since April, as producers' energy costs rose 10.8%. Retail sales rose 0.8% against 0.3% expected, after an upwardly revised 1.3% in August, with gasoline stations up 6.4%. Initial jobless claims were 199,000 against 200,000 expected, and the New York Empire State Manufacturing index jumped to 25.5 from 7.6, its strongest in nearly 5 years.
- Retail sales excluding autos, gasoline, building materials and food services rose only 0.1%, and inflation-adjusted wages fell again, so higher-income households are doing the heavy lifting.
- Risk note: the PPI follows Wednesday's hot CPI, so energy-driven pipeline pressure could keep reaching consumer prices.
4. BONDS/FED: 10-Year Yield Falls 13 Basis Points to 5.06% as Investors Flee to Bonds; Gold Rises to $4,156
The 10-year Treasury Yield fell more than 13 basis points to about 5.06%, a 3-week low, the 30-year to about 5.39% and the 2-year more than 5 basis points to 4.745%. Traders price a 29% to 31% chance of a Fed hike this month, after odds hit an intraday peak of 58% following the CPI, and expect a 25-basis-point hike in December. San Francisco Fed President Daly said further increases will probably be needed but signaled no need to act in October, while Vice Chair for Supervision Bowman said there was time to wait. Spot gold rose 1.2% to $4,156.11 an ounce as the dollar slipped 0.5%. One Investment manager said "two wars need to end before we get any relief."
- The October odds unwound quickly as AI fears and tighter Credit conditions took over from inflation.
- Risk note: the hotter PPI did little to shift expectations of a December hike, so yields could rebound if the tech sell-off eases.
5. MEMORY CHIPS: SK Hynix Is Down 26% in 5 Days as China Competition and an Oversupply Debate Hit the Sector
Over the last 5 days SK hynix has fallen 26%, Samsung 22% and Micron about 11%. China's CXMT announced plans for a server memory product on a new architecture with higher storage density, raising fears of lost market share, though analysts question whether it can scale production at good yields. Traders are also discussing a South Korean column citing 2 experts who expect a "flood of new supply" by 2029, to which Elon Musk replied that China "will be making a LOT of RAM in 2028." Counterpoint Research sees DRAM prices falling about 23% in 2028 from 2027, though still about 230% above 2025, with 3-to-5-year Supply agreements cushioning any downturn.
- Memory makers are expanding capacity, but factories take 3 to 5 years to build, so many analysts see the shortage easing only in 2028.
- Risk note: investors are weighing whether memory's boom-and-bust cycle has changed, and the 2029 oversupply forecast has not been echoed by other analysts.
6. PRE-MARKET MOVERS: Penske Automotive Jumps 8% on a $212 Take-Private Offer, Rocket Lab Falls 10% and Walmart Rises on an Upgrade
Penske Automotive (NYSE:PAG) jumped 8% after saying it will be taken private by Motown Acquisition Corp., owned by Penske Corp. and Mitsui, for $212 per share in cash, a nearly 9% premium to Wednesday's $194.79 close, with closing expected in the first quarter of 2027. Rocket Lab (NASDAQ:RKLB) dropped nearly 10% after delaying the launch of its Neutron rocket to 2027. Walmart (NASDAQ:WMT) rose 2% to 3% after Deutsche Bank upgraded it to buy from hold on a positive 2027 outlook, expecting incremental margins to improve. Crocs (NASDAQ:CROX) rose nearly 2% after Barclays upgraded it to overweight. Merck (NYSE:MRK) rose more than 1% and Eli Lilly (NYSE:LLY) 2%.
- Gains in Walmart and healthcare show money moving outside tech as the AI trade sells off.
- Risk note: Penske's offer is a cash deal at a premium that still has to close, and the first quarter of 2027 is a long wait.
7. MARKET SETUP: Nasdaq-100 Futures Fall 1.3%, Dow Futures Rise 150 Points, Eight States Sue OpenAI and Cboe Extends Options Hours
S&P 500 futures fell 0.3% and Nasdaq-100 futures 1.3%, while Dow futures rose 150 points, or 0.3%. On Wednesday the Dow and S&P 500 also ended lower. European tech shares fell, though less than Asian ones. Eight states, mostly Republican-led apart from Arizona, sued OpenAI, arguing its products harm children and that it lacks sufficient safeguards, and OpenAI said it has "age-appropriate" protections in place. From Monday, Cboe extends trading hours for options on 24 stocks and 5 ETFs, adding 7:30 a.m. to 9:25 a.m. and 4:00 p.m. to 4:15 p.m. ET.
- Pre-market index options averaged a record 228,097 contracts a day last quarter, and the move is another step toward around-the-clock trading.
- Risk note: the OpenAI lawsuits add legal scrutiny to AI companies whose financing is already under question.


 Oct 28, 2026




 Please wait processing your request...