
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
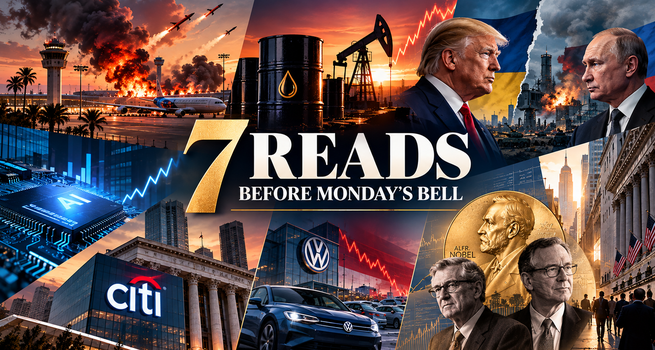
Oil swung between gains and losses after Trump announced a Russia-Ukraine energy ceasefire and a second deadly Houthi strike hit Riyadh's main airport in days, the deadliest Gulf offensive since the Iran war began. Fed rate-hike odds for October have collapsed to below 20% ahead of this week's Inflation data, while more than 4 in 10 S&P 500 stocks are lower this year even as the index sits at record highs.
1. MIDEAST/SAUDI: A 2nd Deadly Strike on Riyadh's Airport in 24 Hours Kills 12 as the US Weighs Joining Saudi Retaliation Against the Houthis
Another missile struck King Khalid International Airport in Riyadh on Sunday, killing 12 people and injuring more than 300, a day after Houthi rebels attacked the same airport, killing at least 13 and injuring more than 300 more. The strikes mark the deadliest offensive against a Gulf Arab country since the Iran war began on February 28, and several Western oil major executives pulled out of an industry event in Riyadh. Trump said the US "may" join Saudi Arabia's retaliation against the Houthis, who have renewed warnings against using Saudi airports outside Mecca and Medina, while the UK's defense secretary said his government is also examining support, though not offensive operations "at this stage." The Houthis have separately tried to choke off tanker traffic through the Bab el Mandeb strait, mirroring Iran's blockade of Hormuz.
- 2 deadly strikes on the same airport within 24 hours, after a Houthi campaign thought largely suppressed, shows the group has regrouped enough to open a 2nd front for US and allied forces already committed to the Iran war.
- Risk note: a US decision to join Saudi strikes would be the first direct American action against the Houthis since a campaign concluded in May 2025, so confirmation either way could move oil sharply given the group's demonstrated reach against both aviation and tanker routes.
2. RUSSIA/UKRAINE: Trump Declares an Energy Ceasefire as Putin Pledges Millions of Tons of Diesel, but Zelensky Says Strikes Continue
Trump declared an "energy ceasefire" between Russia and Ukraine effective Sunday, while Putin pledged to Supply more than 300,000 tons of diesel immediately, followed by 500,000 tons in November and more than 4 million tons in total. Ukraine's president Volodymyr Zelensky said strikes on Russia would continue unless the Kremlin also accepted the truce, noting Russia kept hitting Ukraine's power grid overnight and that Putin "doesn't read Truth Social." Brent Crude swung between a 1.5% loss and a 0.9% gain to trade near $105.68 a barrel, while WTI moved similarly to about $92.72, as the diesel news was offset by Zelensky's pushback and the fresh Saudi attacks. Diesel prices have surged globally since Ukraine began striking Russian refineries, prompting Moscow's export ban, while Iran and the Houthis have separately constrained Middle East refining.
- Oil reversing an initial drop into a gain the same day a ceasefire was announced shows traders treating the Saudi attacks as the bigger near-term supply risk, even against millions of tons of new Russian diesel reaching the market.
- Risk note: Zelensky's conditional acceptance means the ceasefire's durability depends on Russia also halting grid strikes, so a confirmed breach this week would strip out the diesel-relief premium just priced into oil.
3. AI CONCENTRATION: Over 4 in 10 S&P 500 Stocks Are Lower This Year Even as the Index Hits Records, With TSMC Due to Post a 6th Straight Record Quarter
More than 4 in 10 S&P 500 stocks are trading lower in 2026 even as the index itself is up 14% to record highs, with gains concentrated in a handful of chipmakers; memory-chip makers Sandisk (NASDAQ:SNDK) and Micron (NASDAQ:MU) have each more than tripled, while the median S&P 500 stock has gained only about 4%. More than 200 constituents have fallen this year, with a quarter down 11% or more, and fewer than half trade above their 200-day moving average. Technology's 32% sector gain has added more than 10 percentage points to the index versus under 1 point from energy's larger 42% gain; Nvidia (NASDAQ:NVDA) alone has added almost 2%. Taiwan Semiconductor (NYSE:TSM) is expected to report a 65% profit surge to a record Thursday, its 6th straight record quarter.
- A rally this narrow, with over 200 constituents lower while 2 memory-chip makers triple, shows risk concentrated in a smaller set of names than at almost any point in recent memory.
- Risk note: TSMC's results Thursday carry outsized weight for the AI trade given this concentration, so a guidance disappointment would hit index-level gains already resting on a narrow base.
4. Earnings SETUP: Bank Earnings and Citigroup's Push to Resolve 6-Year-Old Regulatory Orders Headline a Heavy Week
Earnings season moves into full swing this week, with major banks reporting alongside Johnson & Johnson (NYSE:JNJ) and UnitedHealth Group (NYSE:UNH) on Tuesday, joined by Wells Fargo (NYSE:WFC) and Citigroup (NYSE:C). Citigroup is separately seeking to rapidly resolve consent orders tied to risk-management and data-governance problems dating to 2020, when a botched $900 million transfer to Revlon creditors triggered Federal Reserve and Office of the Comptroller of the Currency demands and a $400 million fine; Chief Executive Jane Fraser said the bank is about 90% done with the required remediation, which cost $3.3 billion last year. An exit would need Fed and OCC sign-off and could free resources for growth in Citi's Wealth Management division, which returns 12.6% against a long-term goal of 20%.
- Citi targeting a resolution under a Trump administration seen as broadly favorable to banks shows the company racing to lock in an exit before any future change in regulatory posture.
- Risk note: an internal audit already rejected a version of Citi's data-tracing remediation this summer, so a further setback would push back both the consent-order timeline and the growth plans waiting on it.
5. CORPORATE: Volkswagen's Deliveries Fall 14.3% on a 38.5% China Collapse in Its Steepest Drop in 4 Years
Volkswagen reported a 14.3% decline in third-quarter global deliveries to 1.89 million vehicles, its sharpest drop in more than 4 years, as deliveries in China, its largest market, tumbled 38.5% in the quarter and 30.2% over the first 9 months. Deliveries also fell 5.8% in North America and 2.8% in Western Europe while rising 1.4% in Central and Eastern Europe, and global battery-electric vehicle deliveries fell about 5% despite a near 20% increase in Europe, reflecting weaker China Demand and rising domestic competition. Volkswagen is the latest German automaker to report deteriorating China sales after Porsche and Mercedes-Benz posted weaker figures last week.
Seperately, Nasdaq Chief Executive Adena Friedman said that tokenizing Assets could free tens of billions of dollars tied up as collateral.
- 3 major German automakers posting weaker China deliveries in successive weeks shows an industry-wide retrenchment in the world's largest auto market rather than a company-specific stumble.
- Risk note: Volkswagen's battery-electric volumes falling globally even as European EV demand rises nearly 20% shows China's slowdown is large enough to offset growth elsewhere, a dynamic that would deepen if domestic competition keeps intensifying.
6. PRE-MARKET MOVERS: Salesforce Jumps 4% on a Bank of America Upgrade as Iren Pops 5% on a Reported Anthropic Cloud Deal
Salesforce (NYSE:CRM) shares rose 4% after Bank of America double-upgraded the stock to buy, arguing artificial intelligence should "deepen dependence" on the software name rather than disrupt it. Iren (NASDAQ:IREN) shares popped 5.3% after a report said the renewable-energy Data Center operator had quietly signed a multiyear cloud deal with Anthropic. First Solar (NASDAQ:FSLR) gained 2.4% after a Truist upgrade on solar demand and pricing power, while Biogen (NASDAQ:BIIB) rose 2% after a JPMorgan upgrade citing 2027 clinical readouts. SLM (NASDAQ:SLM) advanced 2% after Morgan Stanley upgraded the student-loan administrator to overweight, calling its 15% year-to-date decline a buying opportunity, and Mattel (NASDAQ:MAT) rose more than 1% on a Seaport upgrade amid Takeover speculation. IonQ (NYSE:IONQ) fell more than 2% after agreeing to buy Cybersecurity firm Elisity for up to $1.3 billion. Cocoa rose above $5,600 a tonne, nearly doubling from February's 3-year low, as Ivory Coast and Ghana, the top 2 producers, face below-average rainfall and expected output declines of 11% and 13%.
- A cluster of same-day analyst upgrades across software, solar and biotech, alongside a reported AI infrastructure deal for Iren, shows sector-specific catalysts driving Monday's premarket moves more than any single macro theme.
- Risk note: IonQ's decline on its own Acquisition announcement suggests investors are discounting the near-term financial impact of the Elisity deal, making the stock's reaction to further deal details worth watching this week.
7. MARKET SETUP: Fed Hold Odds for October Surge Above 80% as the Dollar Hits an 18-Month High Ahead of This Week's Inflation Data
US stocks closed higher Friday, with the Dow adding 423 points, or 0.83%, to 51,654.95, the S&P 500 gaining 0.59% to 7,811.54 and the Nasdaq Composite rising 0.64% to 27,366.17; all 3 indexes posted weekly gains, with the S&P 500 up about 1.2%. Traders now price an 81% chance the Fed holds rates steady this month, up from 51% a month ago, with Wednesday's inflation report seen as pivotal. The dollar index traded near an 18-month high at 102.43, supported by Middle East tensions and pared Fed hike bets, while the euro fell for a 5th straight week on French fiscal concerns, with the French-German 10-year Yield spread at 140 basis points. Gold eased to about $4,180 an ounce on dollar strength. Separately, the Nobel Prize in Economics was awarded to Robert Hall and Michael Woodford for work on the microeconomic foundations of macroeconomic stabilization.
- The swing in Fed odds from 51% to 81% within a month, alongside a 5th straight weekly euro decline, shows the dollar's rally driven as much by pared US rate-hike bets and overseas fiscal strain as by domestic strength.
- Risk note: with Wednesday's inflation data the key swing factor, a hot print would force odds back toward a hike just as markets price in a prolonged Fed pause.


 Oct 28, 2026




 Please wait processing your request...