
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
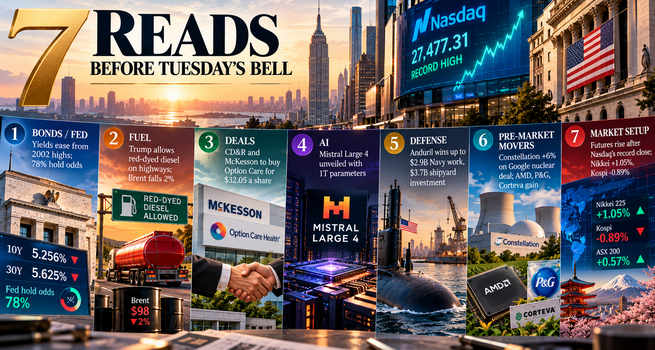
Equity futures rose after the Nasdaq Composite closed at a record 27,477.31 and Treasury yields eased from their highest levels since 2002. Trump allowed cheaper red-dyed diesel on highways, CD&R and McKesson agreed to buy Option Care Health, and Mistral unveiled a new open AI model.
1. BONDS/FED: Treasury Yields Ease From Highest Levels Since 2002 as Fed Hold Odds Reach 78%; Trade Deficit Widens to $105.6 Billion
The 10-year Treasury Yield fell 5 basis points to 5.256% and the 30-year slipped more than 3 basis points to 5.625%, a day after the 10-year closed at its highest since April 2002. Bund yields dropped 5 basis points and French 10-year yields 9. Traders priced a 78% chance the Fed holds at its next meeting, with minutes of the September hike due Wednesday. ISM services read 54.9 for September, just below August, with the prices index up 1.4 points to 74. The August trade deficit widened 13.7% to $105.6 billion against a $102 billion consensus, its widest since March 2025, as imports rose 4.3% on AI buildout goods and tariffs.
- Yields easing as oil fell 2% while the ISM prices index climbed to 74 shows the pullback tracking energy rather than Inflation data.
- Risk note: Wednesday's minutes arrive after the 10-year's highest close since April 2002, so a hawkish read of the September hike could reverse today's 5-basis-point decline.
2. FUEL: Trump Allows Red-Dyed Diesel on Highways and Defers the Federal Tax Through Year-End; Brent Falls 2%
Trump signed an executive order Monday evening allowing truckers and farmers to use red-dyed diesel, exempt from the 24.4-cent-per-gallon highway tax, and directed Treasury to defer the federal excise tax on highway diesel through 2026 without interest or penalties while exploring ways to eliminate it. The national average diesel price topped $6 a gallon in September for the first time, and Americans are spending $700 million more per day on gasoline and diesel than a year ago, per Rapidan Energy. The White House said truckers could save more than $100 per fill-up, citing tight global Supply tied to the war in Ukraine and limited refining capacity. Brent fell 2% to $98 and WTI 2% to $87.
- A 24.4-cent deferral set against diesel above $6 shows relief aimed at the pump ahead of the midterms, since the White House attributes the price to global supply and refining capacity.
- Risk note: with the deferral ending at year-end, the relief depends on a follow-up decision on eliminating the tax before the obligation comes due.
3. DEALS: CD&R and McKesson Agree to Buy Option Care Health for $32.05 a Share; Ariel Presses Mattel to Consider a Sale
Clayton, Dubilier & Rice and McKesson (NYSE:MCK) agreed to buy Option Care Health (NASDAQ:OPCH) for $32.05 per share in cash, an Enterprise value of $5.8 billion. The stock traded at $31.09 pre-market against Monday's $23.37 close, up 33%. CD&R will hold a majority and McKesson a minority interest. Ariel Investments urged Mattel (NASDAQ:MAT) to consider a divestiture, Merger or outright sale, saying a strategic buyer would pay a significant premium. Authentic Brands' reported interest in a $6 billion offer lifted the shares 20% last week, though they are still down 19% this year.
- With Option Care at $31.09 against a $32.05 offer, the pre-market spread is under $1 a share, and the structure gives McKesson outpatient exposure without full ownership.
- Risk note: Mattel's board says it will weigh Ariel's views while a new chief executive arrives, so any approach would meet a stock already up 20% last week.
4. AI: Mistral Unveils Large 4, a 1-Trillion-Parameter Open Model It Calls the Strongest Outside China, Trained on Nvidia GPUs
Mistral unveiled Mistral Large 4, a 1-trillion-parameter model it called the strongest open-weight model developed outside China by a substantial margin. The model was trained over 2 months on 4,000 Nvidia (NASDAQ:NVDA) Grace Blackwell GPUs in Mistral's own European data centers and still lags the frontier in areas such as coding. It launches in preview to developers, Cybersecurity leaders and state authorities before a wider release later this month. Reflection AI, which Nvidia backs, released its first open model Monday and said it matches GLM 5.2, a Chinese model surpassed by GLM 5.3 in August.
- Two Western open models in 2 days, against Chinese systems that remain the most capable open models, show the US-China contest turning on open-weight access.
- Risk note: with general release only later this month, Mistral's claimed lead over Chinese open systems rests on its own statements until independent results arrive.
5. DEFENSE: Anduril Wins Up to $2.9 Billion in Navy Submarine Work and Commits $3.7 Billion to a Baltimore-Area Shipyard
Anduril won a contract worth up to $2.9 billion from the US Navy to boost submarine production and is investing $3.7 billion in a shipyard at Sparrows Point outside Baltimore, slated to start operations in 2030. The site, Arsenal-2, will build Virginia-class components. Anduril said it will create 3,100 jobs and add $2 billion in annual economic output. The award follows the Pentagon's naming of co-founder Palmer Luckey to Project Meridian, alongside Newt Gingrich and SpaceX (NASDAQ:SPCX) chief executive Elon Musk.
- Anduril supplying Virginia-class components days after Luckey joined a Pentagon task force shows defense-tech influence in Washington drawing scrutiny as contractors compete.
- Risk note: with Arsenal-2 not due to start operations until 2030, the $3.7 billion Investment carries multi-year execution risk before it adds to submarine output.
6. PRE-MARKET MOVERS: Constellation Jumps 6% on a Google Nuclear Deal; AMD, P&G and Corteva Rise on Upgrades
Constellation Energy (NASDAQ:CEG) jumped more than 6% and Alphabet (NASDAQ:GOOGL) rose 0.5% after Google agreed to buy power tied to 890 megawatts of new nuclear capacity, plus a separate 2,700-megawatt supply agreement supporting more than $4.3 billion in new Constellation investment. Advanced Micro Devices (NASDAQ:AMD) rose nearly 2% after Citi raised its price target to $800 on CPU Demand driven by Meta's Muse AI agent. Procter & Gamble (NYSE:PG) gained 1.2% after Evercore ISI upgraded it to outperform, and Corteva (NYSE:CTVA) rose nearly 3% after JPMorgan upgraded it to overweight. Lennar (NYSE:LEN) gained 1.5% after Berkshire Hathaway (NYSE:BRK.B) disclosed buying 2.4 million shares.
- All 5 moves come from deals, upgrades or filings rather than earnings, and Constellation's 6% against Alphabet's 0.5% shows the power-supply side of the AI buildout drawing the larger reaction.
- Risk note: AMD's move rests on a CPU-demand thesis tied to Meta's Muse agent, so the price target is exposed to how widely that agent is adopted.
7. MARKET SETUP: Futures Rise After the Nasdaq's Record Close of 27,477.31; Nikkei Gains 1.05% While Kospi Falls 0.89%
S&P 500 futures rose 0.4%, Dow futures gained 248 points and Nasdaq-100 futures added 0.5%, led by AMD up nearly 2% and Nvidia and Broadcom (NASDAQ:AVGO) up just under 1%. On Monday the Nasdaq Composite rose 1.05% to a record close, the Nasdaq-100 gained 0.87%, the S&P 500 rose 0.66% to 7,773.99 and the Dow added 90.94 points to 51,267.90. The S&P 500 sits 0.32% below its Aug. 13 record close of 7,798.99. In Asia, Japan's Nikkei 225 closed up 1.05% at 70,683.98, South Korea's Kospi fell 0.89% to 6,941.39 and Australia's ASX 200 rose 0.57% to 8,735.7, with mainland China closed for Golden Week.
- A Nasdaq record close with the 10-year at its highest close since April 2002 fits Morgan Stanley Wealth Management's view that 6 weeks of bond Volatility has not reached the extremes behind the 2022 Equity bear market.
- Risk note: with the S&P 500 0.32% below its record, Wednesday's Fed minutes are the next test of whether equities keep rallying against the bond selloff.


 Oct 29, 2026





 Please wait processing your request...