
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
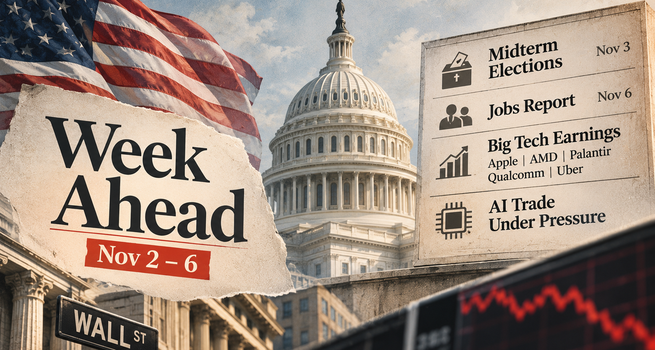
Stocks enter the week on unsteady footing after a bruising Friday session in which the S&P 500 sank 1.8% and the Nasdaq Composite fell 2.9%, dragged lower by disappointing quarterly results from hyperscalers Alphabet and Amazon and a nearly 29% plunge in Intel shares. The selloff has intensified doubts about the financing and returns underpinning the AI Investment theme at the heart of the market's multi-year rally, questions that will persist this week as Apple (NASDAQ:AAPL), AMD (NASDAQ:AMD) and Palantir Technologies (NYSE:PLTR) report results.
Tuesday's midterm elections will determine whether Democrats can wrest control of Congress from President Donald Trump's Republican party, with polls widely favoring a Democratic House while the Senate remains closer to call; investors are watching the outcome for its implications on AI regulation and Data Center pushback as much as fiscal policy. Friday's October employment report is the week's central economic release, with nonfarm payrolls forecast to rise 56,000 after September's 29,000 gain and the Unemployment rate expected to hold at 4.2%. More than 100 S&P 500 companies report this week, with overall third-quarter Earnings on pace to rise 31.6% even as investors have shown little patience for any shortfall, punishing Caterpillar with a 9% drop after a cautious outlook despite strong data center-driven demand.
Major Ex-Dividend Dates This Week
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Monday, Nov 2 |
Realty Income |
$0.42 |
5.49% |
|
|
Monday, Nov 2 |
Marriott International |
$0.25 |
0.72% |
|
|
Tuesday, Nov 3 |
Pfizer |
$0.43 |
6.30% |
|
|
Tuesday, Nov 3 |
MetLife |
$0.59 |
2.59% |
|
|
Wednesday, Nov 4 |
McDonald's |
$1.86 |
2.26% |
|
|
Wednesday, Nov 4 |
Aflac |
$0.58 |
1.90% |
|
|
Thursday, Nov 5 |
ConAgra Brands |
$0.35 |
5.04% |
|
|
Thursday, Nov 5 |
Kimberly-Clark |
$1.22 |
4.09% |
|
|
Friday, Nov 6 |
Wells Fargo |
$0.50 |
2.40% |
|
|
Friday, Nov 6 |
SiriusXM Holdings |
$0.27 |
3.84% |
Monday, November 2
Earnings
Apple (NASDAQ:AAPL) reports after the close, carrying the week's heaviest weight for the broader technology tape after Friday's AI-driven selloff. Apple shares are up roughly 27% so far this year, and investors will focus on iPhone cycle momentum, services Revenue growth, and updates on its AI roadmap. Palantir Technologies (NYSE:PLTR) also reports after the close, offering another read on AI software Demand following Alphabet and Amazon's disappointing hyperscaler results last week. Realty Income (NYSE:O) reports after the close as a real estate investment trust bellwether. Marriott International (NASDAQ:MAR), Williams Companies (NYSE:WMB) and Public Service Enterprise Group (NYSE:PEG) report before the open, alongside IDEXX Laboratories (NASDAQ:IDXX). Diamondback Energy (NASDAQ:FANG) reports after the close with an energy sector read, and Vertex Pharmaceuticals (NASDAQ:VRTX), Estee Lauder and ON Semiconductor (NASDAQ:ON) round out the day.
Economic Data
October's US Manufacturing PMI and the ISM Manufacturing PMI, both prior at 55.9 and 54.5 respectively, land at 9:45 am and 10:00 am ET. September construction spending, prior at 0.9%, closes Monday's calendar.
Tuesday, November 3
Market
US voters head to the polls for midterm elections that will determine control of Congress and shape President Trump's ability to advance his policy agenda for the remainder of his term. All 435 House seats and 35 of the Senate's 100 seats are contested. Democrats are widely predicted to retake the House, while the Senate outcome remains more uncertain; Republicans have controlled both chambers since the start of the Trump administration. Investors are watching for the result's implications on AI regulation and the increasing public pushback against data centers over their energy and environmental impact, with local and state races in Texas and elsewhere also being monitored for their bearing on the broader data center buildout.
Earnings
AMD (NASDAQ:AMD) reports after the close as the week's most direct semiconductor read on the AI trade following Intel's steep post-earnings decline last week. Amgen (NASDAQ:AMGN), Arista Networks (NYSE:ANET) and Booking Holdings (NASDAQ:BKNG) also report after the close. Pfizer (NYSE:PFE) and Marathon Petroleum (NYSE:MPC) report before the open, alongside Apollo Global Management (NYSE:APO), MPLX (NYSE:MPLX), Ametek (NYSE:AME) and Archer-Daniels-Midland (NYSE:ADM). Block (NYSE:XYZ) and AIG (NYSE:AIG) report after the close, while Keurig Dr Pepper (NASDAQ:KDP), Yum! Brands (NYSE:YUM) and Sysco (NYSE:SYY) report before the open. Prudential Financial (NYSE:PRU) closes the day's reports after the close.
Economic Data
JOLTS Job Openings for September, prior at 7.1 million, and factory orders for September, prior at 0.1%, both land at 10:00 am ET, offering a labor demand and Business investment read two days ahead of Friday's more consequential jobs report.
Wednesday, November 4
Earnings
McDonald's (NYSE:MCD) and Uber (NYSE:UBER) report before the open, providing consumer discretionary and Gig Economy reads respectively. Qualcomm (NASDAQ:QCOM) reports after the close with a smartphone chip demand signal that will be read alongside Apple's Monday results. AppLovin (NASDAQ:APP) also reports after the close, extending the week's AI-adjacent earnings slate. CVS Health (NYSE:CVS) and Entergy (NYSE:ETR) report before the open. Aflac (NYSE:AFL), Allstate (NYSE:ALL), MetLife (NYSE:MET), Motorola Solutions (NYSE:MSI), Coherent (NYSE:COHR) and Expedia (NASDAQ:EXPE) all report after the close. Emerson Electric (NYSE:EMR), Datadog (NASDAQ:DDOG) and Grainger (NYSE:GWW) report before the open, while McKesson (NYSE:MCK), Air Products and Chemicals (NYSE:APD) and Edwards Lifesciences (NASDAQ:EW) round out the day's results.
Economic Data
The ADP National Employment Report for October, forecast at 90,000, lands at 8:15 am ET as the first read on private payrolls ahead of Friday's official jobs data. The US trade balance for September, prior at -$105.6 billion, arrives at 8:30 am ET. The US Services PMI and ISM Services PMI for October, prior at 54.9, follow at 9:45 am and 10:00 am ET.
Thursday, November 5
Earnings
ConocoPhillips (NYSE:COP), Parker-Hannifin (NYSE:PH), Southern Company (NYSE:SO), Duke Energy (NYSE:DUK), Cummins (NYSE:CMI), Cigna (NYSE:CI), Targa Resources (NYSE:TRGP), Sempra Energy (NYSE:SRE), Becton, Dickinson and Company (NYSE:BDX), Rockwell Automation (NYSE:ROK), Consolidated Edison (NYSE:ED), Iron Mountain (NYSE:IRM), Kimberly-Clark (NYSE:KMB), Zoetis (NYSE:ZTS) and Cardinal Health (NYSE:CAH) all report before the open. Airbnb (NASDAQ:ABNB) reports after the close, providing a travel and short-term rental demand read. Monster Beverage (NASDAQ:MNST), EOG Resources (NYSE:EOG), Simon Property Group (NYSE:SPG), Axon Enterprise (NASDAQ:AXON), Live Nation Entertainment (NYSE:LYV) and Microchip Technology (NASDAQ:MCHP) also report after the close.
Economic Data
Preliminary third-quarter productivity and costs, prior at 1.4%, land at 8:30 am ET alongside weekly jobless claims for the week ending October 31, prior at 194,000. Cleveland Fed President Beth Hammack delivers remarks at 8:50 am ET, offering the week's clearest look at how the Federal Reserve is weighing the economic data heading into year-end, a day after the Central Bank held interest rates steady and upgraded its assessment of the economy.
Friday, November 6
Earnings
Vistra Corp (NYSE:VST) and Humana (NYSE:HUM) report before the open, closing out the week's earnings calendar.
Economic Data
October's employment report is the week's single most consequential release, landing at 8:30 am ET. Nonfarm payrolls are forecast to rise 56,000, up from September's 29,000 increase, with the unemployment rate expected to hold at 4.2% and average hourly earnings forecast to accelerate to 0.3% month-on-month from 0.1%. The report arrives after third-quarter GDP data this week showed the economy growing at its fastest pace in a year, driven by resilient consumer spending and heavy AI-related business investment, a combination some economists have flagged as masking a notable absence of job growth. Federal Reserve Bank of St. Louis President Alberto Musalem speaks at 9:10 am ET. The preliminary November University of Michigan Consumer Sentiment Index, prior at 46.3 and forecast at 47.2, lands at 10:00 am ET, with Fed Governor Michelle Bowman speaking at 12:15 pm ET. September consumer credit, prior at $8.3 billion, closes the week's data calendar at 3:00 pm ET.
Geopolitical Backdrop
Beyond Tuesday's midterm vote, the market continues to weigh fallout from one of the roughest weeks of the AI trade this year. Alphabet and Amazon, two of the hyperscalers spending most heavily on data center buildout, both delivered results that intensified scrutiny of whether AI-related Capital Expenditure is converting into durable returns, while Intel's nearly 29% single-day decline underscored how unforgiving investors have become toward any shortfall against elevated expectations. A Democratic sweep of Congress is expected to bring additional regulatory scrutiny to the AI buildout, Wall Street banks and crypto firms alike, while a split or Republican-held outcome would likely be read as preserving the status quo on fiscal and regulatory policy. Away from Washington, other parts of the market have picked up the slack from softening AI sentiment, with energy, financials and defensive sectors such as utilities and healthcare posting solid gains in October, a sign the rally has broadened beyond the small group of companies that drove most of 2026's gains.
The Week in Context
Three threads converge to make this one of the more consequential weeks of the fourth quarter. First, whether Apple, AMD and Palantir can deliver results and guidance strong enough to steady a market still absorbing Alphabet, Amazon and Intel's disappointments, or whether the AI trade's recent turbulence has further to run.
Second, whether Tuesday's midterm results reshape the regulatory outlook for AI, technology and data center expansion enough to matter for valuations already under pressure.
Third, whether Friday's jobs report confirms the labor market softness that has become the most visible crack in an otherwise resilient economic growth narrative, one that has so far been carried by consumer spending and AI investment rather than hiring.
A week that delivers reassuring tech earnings, a market-friendly election outcome and a jobs report in line with expectations would go a long way toward restoring confidence that October's gains, the S&P 500 remains up more than 10% on the year, rest on firmer ground than last Friday's selloff suggested.

 Nov 03, 2026
 Please wait processing your request...