
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Thursday, with the S&P 500 gaining 0.8%, the Nasdaq rising 1.3%, and the Dow adding 139 points as renewed strength in semiconductor and AI-linked shares lifted sentiment. Strong demand for SK Hynix’s US offering supported memory-chip stocks, driving gains in Micron, Sandisk and Applied Materials, while Meta advanced after outlining plans to begin producing its own AI chip by September. Easing oil prices and Treasury yields also supported financial stocks as continued tanker traffic through the Strait of Hormuz reduced concerns over supply disruptions and inflation.
Market Movers
Among the top-performing stocks of the session Nuvve Holding Corp, Inc. surged 63.58%, while Tvardi Therapeutics, Inc. rallied 61.29%. On the losing side, Sadot Group Inc. fell 49.23%, while. Julong Holding Limited declined 29.17%, making them the weakest performers during the trading day.
Commodities Update
WTI and Brent crude held above USD 72 and USD 76 per barrel, respectively, on Friday and were set for weekly gains of nearly 5% and 6% as renewed US-Iran strikes slowed the recovery in tanker traffic through the Strait of Hormuz. Although longer-term negotiations between Washington and Tehran remained ongoing, the IEA warned that a prolonged conflict could hinder the rebuilding of global oil inventories following recent supply losses. Vessel activity through Hormuz remained well below normal, keeping regional supply risks elevated, although record crude production from the UAE highlighted efforts by Gulf producers to offset disruptions.
Gold held above USD 4,100 per ounce and was set to end the volatile week broadly unchanged, while silver traded near USD 60 and remained on course for a weekly decline as investors assessed renewed US-Iran hostilities, ongoing peace talks, and their implications for energy flows, inflation and monetary policy. Recent strikes and retaliatory attacks disrupted traffic through the Strait of Hormuz, reviving inflation concerns, while markets continued to price in at least one Federal Reserve rate increase this year despite significant policy uncertainty. New York Fed President John Williams also highlighted AI-driven demand as an important source of US inflationary pressure.
Macro Updates
The US dollar index fell toward 100.5 on Friday, extending losses for a third consecutive session as renewed US-Iran peace talks reduced safe-haven demand and softer oil prices eased inflation concerns. Although markets continued to expect at least one Federal Reserve rate increase this year, the dollar weakened broadly, with the sharpest declines against the Japanese yen and New Zealand dollar. Meanwhile, New York Fed President John Williams highlighted AI-driven demand as an inflation risk, while Fed Chair Kevin Warsh’s review of key policy areas signalled potential changes to the central bank’s monetary framework.
Bonds Commentary
The US 10-year Treasury yield eased to around 4.54% on Friday, extending its decline for a second session as softer oil prices reduced inflation concerns and expectations of aggressive monetary tightening. Although renewed US-Iran peace talks supported sentiment, markets still anticipated at least one Federal Reserve rate increase this year. New York Fed President John Williams highlighted AI-driven demand as a key inflation risk, while Fed Chair Kevin Warsh announced five task forces to review major areas of central bank policymaking, indicating possible changes to the Fed’s policy framework.
Futures Update
US stock futures were mixed on Friday, with S&P 500 contracts edging lower and Nasdaq 100 futures falling nearly 1% as chipmakers, including Micron and Sandisk, gave back part of the previous session’s gains. Although strong demand for SK Hynix’s domestic listing and higher investment guidance from Micron supported enthusiasm around AI infrastructure and memory stocks, easing Treasury yields and stabilising oil prices provided relief to financials and other traditional sectors, helping Dow futures move slightly higher. Delta Air Lines also gained around 2% premarket following strong earnings and a dividend increase.
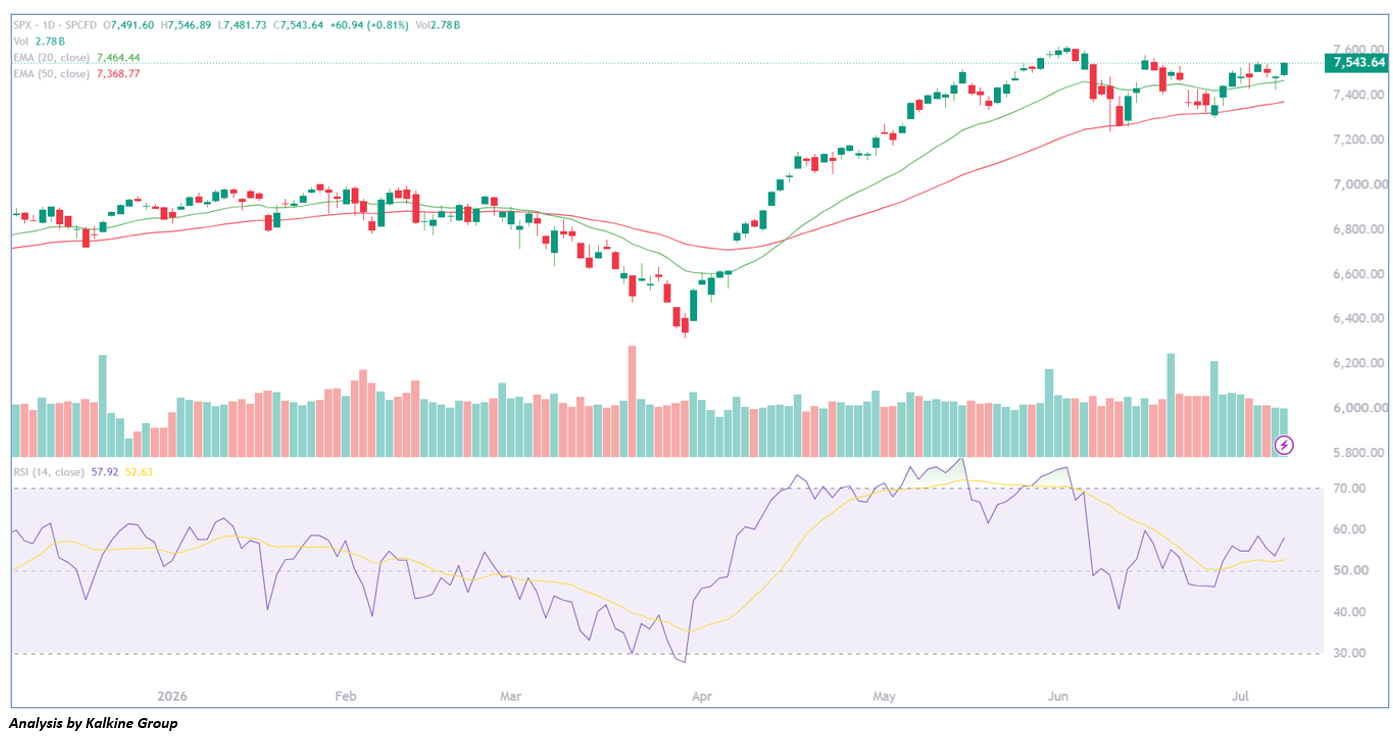
After experiencing notable volatility in early trading, U.S. stocks gained strength throughout Thursday's session, with the major averages finishing higher following Wednesday's mixed performance. The Nasdaq led the advance as technology stocks attracted renewed buying interest, providing the primary support for the broader market. From a technical perspective, the S&P 500 continues to exhibit a constructive near-term outlook, trading comfortably above both its 20-day EMA (7,464) and 50-day EMA (7,369). The index remains in a consolidation phase near record highs, while the RSI around 58 points to strengthening momentum without signaling overbought conditions. As long as the S&P 500 holds above the 20-day EMA, the bullish trend is expected to remain intact, with a breakout above the current consolidation range potentially paving the way for fresh all-time highs.

 Nov 04, 2026

 Please wait processing your request...