
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed mostly lower on Monday as escalating Middle East tensions, volatile oil prices and rising Treasury yields weighed on broader sentiment. The S&P 500 declined 0.2%, the Dow fell 307 points and the Nasdaq 100 finished nearly flat. Banks and manufacturers retreated, while semiconductor stocks rebounded, led by Broadcom, Micron, AMD and Intel. Alphabet gained 1.5% ahead of its guidance update.
Market Movers
Among the top-performing stocks of the session Zhengye Biotechnology Holding Limited. surged 1,047.56%, while Advanced Biomed Inc. rallied 76.94%. On the losing side, Niki BioSolutions, Inc. fell 87.39%, while Columbia Financial, Inc. declined 54.55%, making them the weakest performers during the trading day.
Commodities Update
Brent crude rose toward USD 89 per barrel, while WTI climbed above USD 83, as escalating Middle East tensions outweighed hopes for diplomatic progress. The US continued strikes on Iran for a tenth consecutive day, while Tehran retaliated with missile and drone attacks targeting Kuwait. Although Iran confirmed receiving mediation proposals and reports suggested discussions over a possible 10-day ceasefire, oil prices remained volatile. Supply concerns intensified after Yemen’s Houthi movement threatened Saudi shipping in the Red Sea, prompting Saudi Arabia to pledge measures to protect the key export route.
Gold climbed more than 1% to USD 4,070 per ounce, while silver surged over 4% to USD 59, as investors assessed diplomatic efforts to ease the US–Iran conflict and secure shipping through the Strait of Hormuz. Although reports of a possible 10-day truce supported hopes for de-escalation, the conflict’s impact on oil prices intensified inflation concerns and expectations that US interest rates could remain elevated or rise further. The Federal Reserve is widely expected to hold rates steady next week, while markets assign more than a 60% probability to a September rate hike.
Macro Updates
Dollar Holds Near 101 Amid Inflation and Rate-Hike Concerns
The US dollar index traded near 101 after three consecutive sessions of gains, supported by rising oil prices and expectations that escalating US–Iran tensions could intensify inflationary pressures. While mediation efforts and reports of a possible 10-day ceasefire offered hopes of de-escalation, threats to Red Sea energy shipments kept markets cautious. Investors now see around a 55% probability of a Federal Reserve rate hike in September, although rates are expected to remain unchanged at next week’s meeting.
Bonds Commentary
The US 10-year Treasury yield held near 4.6% as continued US–Iran hostilities and threats to Red Sea shipping pushed oil prices higher, intensifying inflation and monetary-tightening concerns. Although mediation proposals offered some hope of de-escalation, markets raised the probability of a September Federal Reserve rate hike to around 55%, while policymakers are widely expected to leave rates unchanged at next week’s FOMC meeting.
Futures Update
US stock futures advanced on Tuesday, led by technology shares, with S&P 500 and Dow futures rising about 0.5% and Nasdaq 100 futures gaining nearly 1%. Alphabet and Tesla climbed ahead of their upcoming earnings, while strong export data from Taiwan and South Korea supported semiconductor stocks. Markets remained resilient despite escalating US–Iran tensions, elevated energy prices and high Treasury yields. Among earnings movers, GM rose 2% following its results, while Charles Schwab fell 3% after missing estimates.
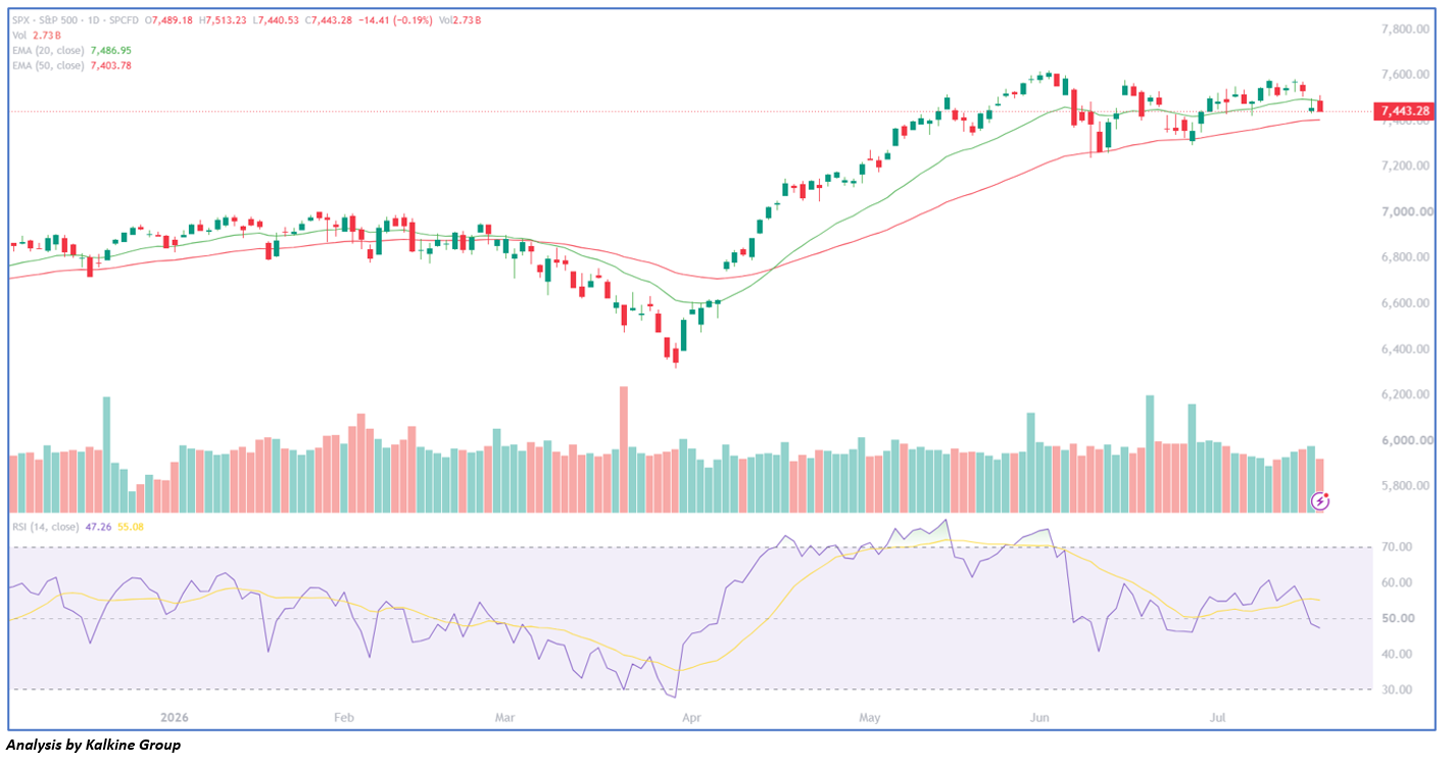
Stocks showed a strong move to the upside in early trading on Monday but surrendered those gains as selling pressure intensified throughout the session. The major averages reversed sharply from their intraday highs and closed in negative territory, reflecting weakening market sentiment. The S&P 500 has turned cautiously bearish in the near term after failing to hold above the 20-day EMA (7,487). Although the index remains above the 50-day EMA (7,404), the loss of short-term momentum and an RSI near 47 suggest that sellers currently have the upper hand. Immediate support is seen in the 7,420–7,400 zone, and a decisive break below this level could accelerate downside pressure toward lower support areas. On the upside, 7,500–7,530 remains a key resistance zone, with any rebound likely to face selling interest unless the index reclaims and sustains levels above the 20-day EMA.

 Nov 17, 2026
 Please wait processing your request...