
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Friday as optimism over the upcoming Earnings season lifted sentiment. The S&P 500 rose 0.6%, the Nasdaq 100 gained 0.5% and the Dow added 423 points. Major banks advanced ahead of an expected nearly USD 19 billion in quarterly stock-trading revenue, while Alphabet, Microsoft and Amazon gained on expectations that OpenAI’s annualised Revenue could exceed USD 70 billion by year-end. For the week, the S&P 500 gained 0.9%, the Nasdaq slipped 0.1% and the Dow rose 585 points.
Market Movers
Among the top-performing stocks of the session WF Holding Limited. surged 499.51%, while Veea Inc. rallied 47.29%. On the losing side, Moolec Science SA. fell 47.49%, while Armada Acquisition Corp. II. declined 29.38%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded above USD 92.5 per barrel and Brent exceeded USD 105.5 on Monday as renewed attacks on Saudi Arabia’s main airport and a tanker in the Strait of Hormuz heightened Middle East Supply concerns. However, Persian Gulf shipments reportedly recovered to 17.5 million barrels per day, nearly 98% of pre-war levels. Meanwhile, President Trump claimed Russia and Ukraine had agreed to an immediate energy ceasefire, while limited Russian diesel exports prompted the IEA to urge faster releases of pledged diesel supplies ahead of its October 15 meeting.
Gold eased to around USD 4,180 an ounce and silver declined to USD 60.7 on Monday as the US dollar hovered near an 18-month high. Investors awaited US Inflation and retail sales data, with stronger readings potentially lifting Treasury yields and reinforcing expectations of tighter Federal Reserve policy. Traders priced in less than a 20% probability of a rate hike this month and an 85% chance by December, while monitoring the IMF–World Bank annual meetings for further policy signals.
Macro Updates
Dollar Holds Above 102 Ahead of US Inflation Data
The dollar index held above 102 on Monday after four consecutive weekly gains as investors awaited US inflation reports for clues on Federal Reserve policy. Stronger readings could intensify bond selling and expectations of further tightening, with markets pricing an 83% chance of unchanged rates this month and an 86% probability of a December hike. Meanwhile, hopes of additional Russian diesel supplies and an immediate Russia–Ukraine energy ceasefire weighed on oil prices, easing inflation concerns.
Bonds Commentary
The US 10-year Treasury Yield edged up to 5.26% on Friday as investors assessed Middle East developments and persistent inflation risks, despite easing oil prices. Markets priced an 81% chance of unchanged Fed rates this month and a 69% probability of a 25-basis-point hike in December. The yield declined around 5 basis points over the week, while the Treasury cash market will remain closed on Monday for a holiday, with futures trading continuing.
Futures Update
US Equity futures were largely unchanged on Monday as strong earnings expectations offset concerns over elevated bond yields and tighter Credit conditions, with S&P 500 and Nasdaq 100 contracts testing record highs. Higher energy prices amid the Middle East conflict sustained concerns about further Federal Reserve rate hikes. Premarket, Meta gained 2% and Salesforce rose 4%, while Micron, AMD and Marvell declined around 2% each amid continued Volatility in AI infrastructure stocks. 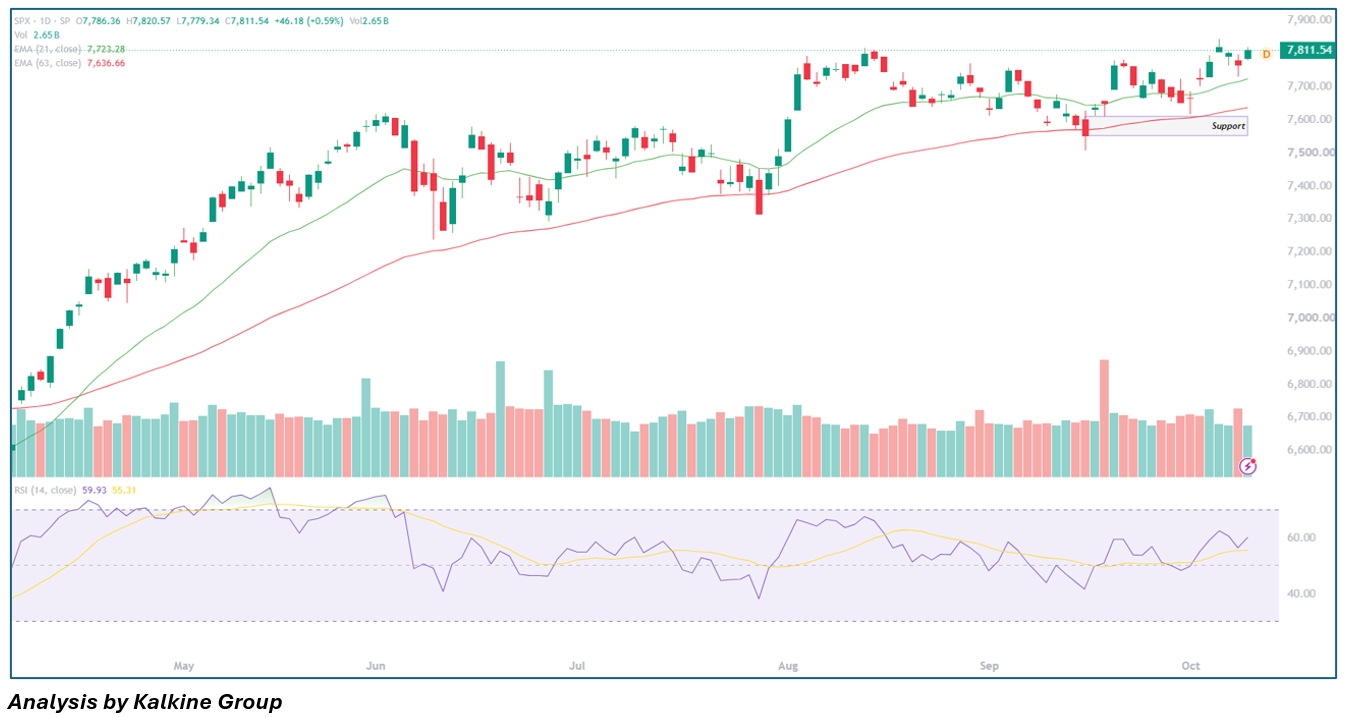
U.S. stocks bounced back on Friday after coming under pressure in the previous session, and the major averages all closed firmly higher. The S&P 500 (SPX) gained 0.59% to finish at 7,811.54 on Volume of 2.65B, and the short-term view is bullish. The index opened at 7,786.36 and traded between 7,779.34 and 7,820.57, closing near the top of that range. The green candle wins back part of the losses from the previous two sessions. The 21-day EMA (7,723.28) and 63-day EMA (7,636.66) are both rising and sit below price, so the uptrend remains intact, with the index about 1.1% above its 21-day EMA. RSI at 59.93 has turned up from the mid-50s and is above its 55.31 signal line, a sign that momentum is improving. The index still has to clear the recent spike high near 7,830 to 7,840, and a close above that zone would confirm a breakout from the range in place since August. A move below today's low at 7,779 would bring the 21-day EMA near 7,723 into focus, with the 7,550 to 7,600 zone, which held in September, as the key support below. This is a technical read, not Investment advice.

 Nov 02, 2026

 Please wait processing your request...