
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks fell on Monday as the US–Iran standoff drove oil prices and Treasury yields higher, raising concerns about Inflation and further Fed rate hikes. The S&P 500 lost 0.8%, the Dow fell 347 points and the Nasdaq declined 1.1%, with major technology and chip stocks among the weakest performers. Nvidia bucked the trend, gaining 1.7% after expanding its share buyback plan. Investors now await this week’s PCE inflation and jobs reports for clues on the Fed’s next move.
Market Movers
Among the top-performing stocks of the session Kodiak Sciences Inc. surged 177.96%, while Lifecore Biomedical, Inc. rallied 55.24%. On the losing side, Neo-Concept International Group Holdings Limited. fell 83.75%, while Masonglory Limited. declined 61.21%, making them the weakest performers during the trading day.
Commodities Update
WTI and Brent Crude eased on Tuesday as renewed US–Iran mediation efforts and the partial restoration of Saudi Arabia’s East–West pipeline reduced immediate Supply concerns. The pipeline is moving about 3.5 million barrels a day to the Red Sea, offering an alternative to the Strait of Hormuz. A diplomatic breakthrough remains uncertain, however, with disagreements over the strait’s reopening and sanctions relief unresolved.
Gold and silver steadied on Tuesday after sharp losses in the previous session, trading near USD 4,100 and USD 60.5 an ounce, respectively. Uncertainty over US–Iran talks has kept oil prices elevated, adding to inflation concerns and pushing Treasury yields higher. With markets assigning roughly a 70% chance to another Federal Reserve rate hike in October, attention turns to this week’s US PCE inflation and jobs data for clues on the policy outlook.
Macro Updates
Dollar Holds Near Two-Month High on Fed Rate-Hike Expectations
The dollar index traded around 101.2 on Tuesday as uncertainty over US–Iran negotiations kept oil prices and Treasury yields elevated. Energy-driven inflation concerns strengthened expectations of further Federal Reserve tightening, with markets pricing in roughly a 70% chance of an October rate hike. Fed Governor Lisa Cook also warned that near-term price pressures could outweigh potential productivity gains from AI.
Texas Manufacturing Sentiment Eases as Cost Pressures Rise
The Dallas Fed’s general Business activity index edged down to 9.8 in September from 11.6 in August, while the company outlook index fell more sharply to 8.7. Employment growth strengthened, but manufacturers reported faster increases in raw material prices, finished goods prices and wages. Expectations remained positive, although the future general business activity index declined to 20.8 from 37.2.
Bonds Commentary
The US 10-year Treasury Yield held near 5.24% on Tuesday after reaching its highest level since mid-2007 in the previous session. Stalled US–Iran talks and elevated oil prices kept inflation and further Fed rate hikes in focus, while strong US activity and concerns over government borrowing added pressure to bonds. The yield has risen nearly 46 basis points in September, with investors awaiting this week’s economic data for further direction.
Futures Update
US stock futures edged higher on Tuesday after the previous session’s losses, led by a modest rise in Nasdaq 100 futures. AI developments remained in focus ahead of OpenAI’s DevDay, while uncertainty in the Middle East, volatile oil prices and elevated Treasury yields kept investors cautious. Most major technology stocks gained in premarket trading, though Apple and Microsoft slipped.
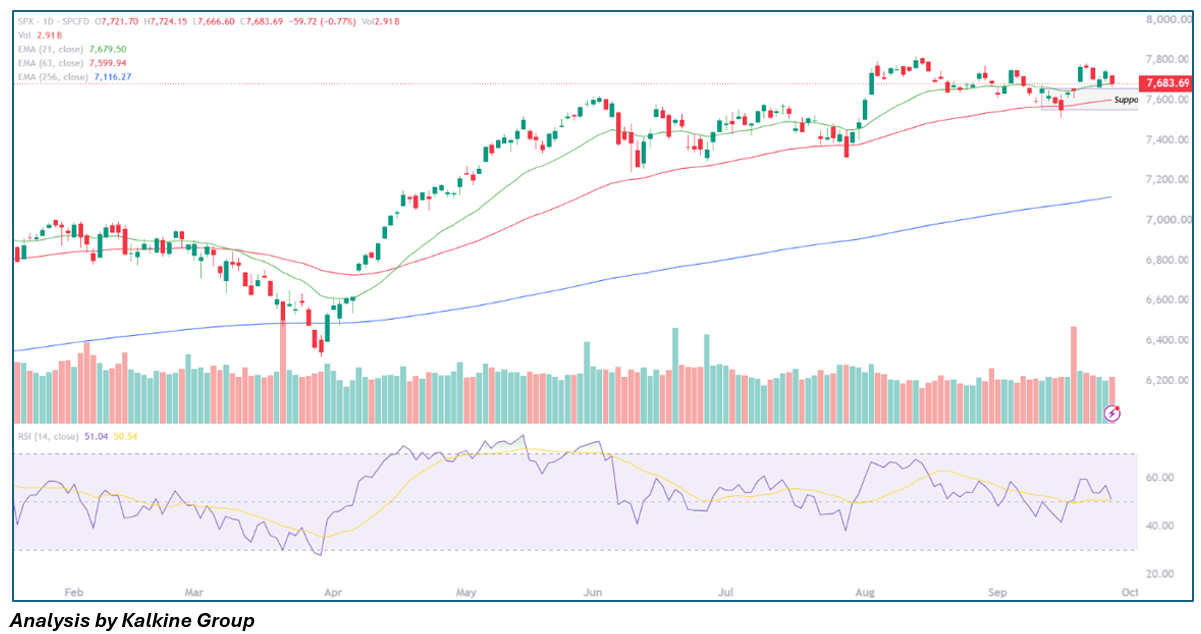
Stocks came under pressure early on Monday and spent the session fluctuating, ending mostly lower. All the major averages moved down, giving back some of the strength from last Friday. The S&P 500 closed at 7,683.69, off about 0.77%, after being turned back near 7,721–7,724. It is now trading close to the 21-EMA (7,679.50) and just above the 63-EMA (7,599.94), with a clear support zone sitting around 7,550–7,650. RSI is flat near 51, which points to neutral momentum, and the red candle came on roughly average volume, suggesting mild profit-taking rather than heavy selling. The bias stays neutral to cautiously bullish as long as the index holds above 7,680 and the 7,600 support area. A slide below 7,600 would bring 7,550 into play, while a move back above 7,720–7,780 would open the way to a retest of the 7,800+ highs. The 7,680 level is the pivot to watch for direction. The wider uptrend remains intact, with price well above the rising 256-EMA (7,116).

 Nov 03, 2026

 Please wait processing your request...