
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
Wall Street slipped for a second straight session Tuesday ahead of Wednesday's Inflation report. The S&P 500 dropped 0.32% to close at 7,728.20, the Nasdaq Composite fell 0.60% to 26,445.45, and the Dow Jones Industrial Average shed 184.13 points, or 0.34%, to 53,791.85. The pullback came as an intensifying US-Iran standoff raised doubts about progress on reopening the Strait of Hormuz just ahead of the inflation data. Energy and healthcare stocks led the sector gainers, while real estate and technology names finished in the red; Nvidia gave back early gains to close roughly flat as investors digested its $500 billion AI-infrastructure financing plan. Alphabet was a notable laggard, sinking more than 3.6% on the session.
Market Movers
Plug Power and Riot Platforms both jumped around 12% on stronger-than-expected quarterly results, while Sea Limited rose about 10% after posting Revenue of $7.79 billion, up 48% year-over-year.
Commodities Update
Oil stayed elevated but choppy. US crude settled near $83 as Iran reiterated it would keep the Strait shut until its demands are met, even as earlier optimism from Pakistani officials about a possible arrangement briefly pulled prices lower. Heading into Wednesday's Asia session, oil and gold both climbed further as tensions ratcheted up, with the US and Yemen's Iran-aligned Houthis reporting separate shipping attacks and North Korea carrying out an early-morning missile launch.
Gold eased to around $4,382 and silver slipped to about $64.78 on Tuesday as firmer oil lifted yields and traders trimmed positions ahead of the CPI print, though steady Chinese institutional and central-bank buying kept physical Demand firm.
Macro Updates
CPI Day Has Arrived
The Bureau of Labor Statistics releases the July CPI at 8:30 a.m. ET, with economists expecting annual inflation of 3.4%, down from June's 3.5%. Core CPI, which excludes food and energy, is expected to rise 0.2% for the month and ease to 2.5% annually from 2.6%. Some bottom-up estimates put core CPI close enough to the rounding line that it could land at either 0.2% or 0.3%, which would keep the headline year-over-year figure at 3.5% instead of the consensus 3.4%.
Fed Odds Still a Coin Flip
Rate-hike pricing has been volatile and sources disagree slightly on the exact number, but the broad picture is a near 50/50 market. July payrolls fell by 23,000, which had initially pushed September rate-hike odds into the low-40% range before oil's rebound lifted that probability back to roughly 52%. CME Group's FedWatch data showed roughly 50-50 odds between the Fed raising rates or holding steady at next month's meeting, with today's CPI reading likely to shift that balance.
NFIB Small-Business Optimism
This figure was already released and covered in yesterday's note — no new data point today. The July reading (99.8, up 2.4 points) was its highest since August 2025 and above the 52-year average.
Bonds Commentary
The 10-year Treasury Yield climbed more than 4 basis points to 4.705% at the start of the week, with the 30-year up a similar amount to 5.251%, as oil prices and a heavy data calendar kept pressure on the long end. By Tuesday it was holding near 4.74%, close to its highest level since January 2025.
Futures & Early Wednesday Setup
Oil and gold extended gains into Wednesday's Asian session as geopolitical risk built further, while the yen weakened against the dollar after unwinding much of last week's intervention-driven rally. The dollar index rose 0.07% to 99.88. Regional Asian shares were firmer heading into the US session, with all eyes on the 8:30 a.m. ET inflation number.
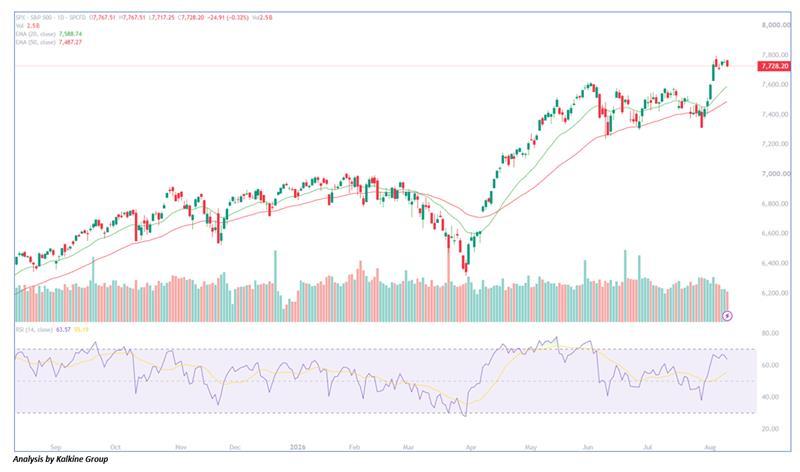
After starting the session with limited direction, stocks came under pressure throughout Tuesday’s trading, with all the major averages ending lower and extending the modest declines from the previous session. Although the indexes recovered somewhat from their intraday lows, they remained in negative territory at the close. The S&P 500 continues to maintain a bullish intraday bias, holding comfortably above its 20-day EMA at 7,589 and 50-day EMA at 7,487, which keeps the broader uptrend intact. Momentum remains constructive following the recent breakout toward 7,750, while the RSI at 63.6 indicates healthy bullish momentum without reaching overbought levels. Immediate support is positioned around 7,700–7,680, and a hold above this zone could pave the way for a retest of 7,750–7,800. A decisive move above 7,750 would strengthen the bullish setup, whereas a break below 7,680 could lead to near-term consolidation.

 Nov 03, 2026

 Please wait processing your request...