
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Wednesday as hotter-than-expected Inflation reinforced expectations of another Fed rate hike, while AI infrastructure concerns and rising Chinese competition pressured chipmakers. The S&P 500 fell 1.1%, the Nasdaq dropped 2% and the Dow lost 49 points. Nvidia, Broadcom, Micron and AMD declined between 3.1% and 5.7%. Bank of America fell 4.8% on weaker-than-expected trading revenues, while Morgan Stanley lost 2.7% despite strong equity-trading results. BlackRock gained 0.7% as stronger inflows boosted fee revenue.
Market Movers
Among the top-performing stocks of the session Greenland Energy Company. surged 76.47%, while Bending Spoons S.p.A. rallied 41.20%. On the losing side, Republic Power Group Limited. fell 65.19%, while Black Hawk Acquisition Corporation. declined 37.98%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded near USD 95 per barrel and Brent eased to around USD 104 on Thursday as escalating Middle East shipping risks competed with weakening Demand expectations. A vessel sinking in the Strait of Hormuz, Iranian threats against US warships and Houthi attacks on Saudi Arabia heightened Supply concerns. The IEA warned of persistent diesel shortages and decade-low land-based inventories, while forecasting global oil demand would contract by 2.6 million barrels per day in 2026. Meanwhile, industry data showed US crude inventories fell by 11.1 million barrels last week.
Gold recovered toward USD 4,150 per ounce and silver steadied above USD 56 on Thursday, supported by a softer dollar, lower bond yields and the end of crude oil’s five-day rally. However, expectations of further Federal Reserve rate hikes limited sentiment after September US inflation reached 3.7%, exceeding forecasts of 3.6%, largely due to higher energy costs. Chicago Fed President Austan Goolsbee warned of potential overheating from AI infrastructure spending, while San Francisco Fed President Mary Daly signalled that further tightening might be needed, although she saw no immediate need for a hike this month.
Macro Updates
US PPI Expected to Accelerate Monthly Despite Easing Annual Inflation
US producer prices are forecast to rise 0.5% month-over-month in September 2026, up from 0.4% in August, marking a third consecutive acceleration amid elevated energy costs. Core PPI is expected to increase 0.3%, versus 0.2% previously. However, annual headline and core producer inflation are projected to ease to 5.3% and 4.4%, respectively, from 5.4% and 4.6%.
Dollar Retreats as Investors Assess Fed Rate Outlook
The US dollar index eased toward 102 on Thursday from 18-month highs as investors weighed stronger-than-expected September inflation against cautious Federal Reserve policy signals. Headline and Core Inflation reached 3.7% and 2.6%, respectively, prompting concerns about economic overheating. However, markets priced in a roughly 73% chance of unchanged rates this month. Investors awaited remarks from Fed Chair Kevin Warsh, while the dollar weakened most against the euro, sterling and New Zealand dollar.
US Crude Inventories Record Largest Draw Since January
US crude inventories fell by 11.12 million barrels in the week ended October 9, sharply contrasting with expectations for a 1.9 million-barrel increase and following a 2.09 million-barrel decline previously. Cushing stocks rose by 1.82 million barrels. Separately, gasoline inventories increased by 1.1 million barrels and distillates fell by 1.5 million barrels in the week ended October 7, while crude production reached 13.98 million barrels per day in the week ended October 2.
Bonds Commentary
The US 10-year Treasury Yield fell to a three-week low near 5.11% on Thursday, reversing the previous session’s peak of 5.33%, as a technology-led Equity selloff drove demand for safe-haven bonds. September headline and core inflation exceeded forecasts at 3.7% and 2.6%, respectively, raising concerns about further monetary tightening. However, cautious signals from some Fed policymakers kept market expectations at roughly a 73% probability of unchanged rates this month.
Futures Update
US equity futures were mixed as concerns over AI spending returns weighed on technology stocks. S&P 500 and Nasdaq 100 futures fell 0.3% and 1.3%, respectively, after Anthropic’s weaker-than-expected third-quarter sales intensified investor caution. Micron, Intel, AMD and Marvell dropped over 4% premarket, while Seagate and Western Digital fell 6%. Expectations of stronger producer inflation reinforced prospects of another Fed rate hike this year. Meanwhile, the Dow edged higher alongside a Treasury rally, with Walmart gaining 2.6% and Eli Lilly rising 2%. 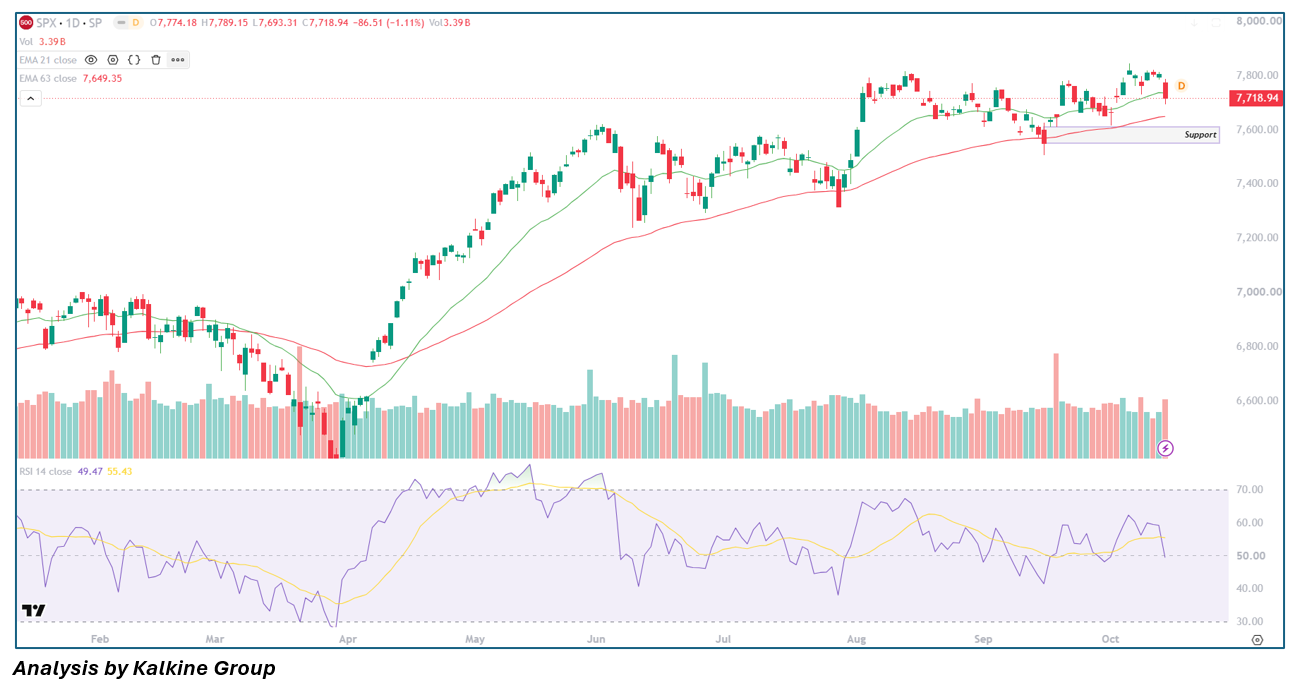
Stocks extended their slide on Wednesday after a choppy, modestly lower session the day before, with the tech-heavy Nasdaq taking the steepest hit. The major averages recovered from their worst levels into the close but still finished in the red. The S&P 500 opened near 7,774, touched a high of 7,789, then dropped to a low of 7,693 before settling around 7,719, down about 86 points (-1.11%). The sharp Reversal from a positive open left a large red candle that closed below the 21-day EMA (roughly 7,740s) for the first time in a while, on elevated Volume of 3.39B shares. RSI fell to about 49, below both its signal line (~55) and the 50 midline, pointing to fading momentum. The key question now is whether the index holds above the 63-day EMA (~7,649) and the support zone near 7,550-7,600, since a break lower would raise the risk of a deeper pullback. A quick move back above the 21-day EMA would instead suggest a shakeout within the broader consolidation beneath the 7,800-7,850 highs. This is technical commentary only, not financial advice.

 Nov 19, 2026
 Please wait processing your request...