
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks declined on Tuesday as semiconductor weakness and rising macroeconomic concerns weighed on sentiment. The S&P 500 fell 0.7% and the Nasdaq 100 dropped 2.7%, while the Dow retreated from a record high. Micron, Sandisk, Applied Materials and AMD posted sharp losses amid growing doubts over AI infrastructure spending and reports of new Chinese chip development. Higher bond yields and renewed energy-inflation concerns also pressured industrial stocks, including Caterpillar, Deere and GE Vernova.
Market Movers
Among the top-performing stocks of the session Crinetics Pharmaceuticals, Inc. surged 98.74%, while ClearOne, Inc. rallied 97.71%. On the losing side, Lianhe Sowell International Group Ltd. fell 41.32%, while. WF Holding Limited declined 31.65%, making them the weakest performers during the trading day.
Commodities Update
WTI and Brent crude prices jumped 6% to USD 74.5 and USD 78.5 per barrel, respectively, as renewed US-Iran hostilities heightened concerns over supply disruptions through the Strait of Hormuz. US strikes on Iran, the withdrawal of an oil-sales waiver, attacks on commercial vessels and Iran’s reported retaliation against US military sites raised fears that shipping and regional production could be disrupted. The escalation sharply reversed earlier expectations of an oversupplied market following higher OPEC+ production quotas and planned output increases by Middle Eastern producers.
Gold and silver declined more than 1% and 2% to USD 4,050 and USD 58.4 per ounce, respectively, after renewed US-Iran tensions pushed oil prices sharply higher and increased concerns over inflation and tighter US monetary policy. President Trump declared the interim peace arrangement with Iran over, while Tehran reported retaliatory strikes on US military bases following fresh US actions. Markets raised the probability of a September rate hike to 66%, while investors awaited the Federal Reserve’s June meeting minutes for further policy guidance. Gold received some support from China’s largest monthly reserve increase in over two and a half years.
Macro Updates
Mortgage Rates Edge Higher as Applications Decline
The average US 30-year fixed mortgage rate increased to 6.58% in the week ended July 3, 2026, from 6.57% previously, remaining near a nine-month high as Treasury yields rose amid inflation and interest-rate concerns. Total mortgage applications fell 2.2%, with refinancing activity down 4.1% and purchase applications declining 0.6%, despite signs of a cooling labour market and the Federal Reserve indicating no urgency to raise rates.
Dollar Holds Firm as Rate-Hike Expectations Rise
The US dollar index remained above 101 near a one-week high as renewed US-Iran tensions pushed oil prices sharply higher and revived inflation concerns. Markets increased the implied probability of a September Federal Reserve rate hike to around 70% from 58% previously, while investors awaited the FOMC meeting minutes for further guidance on the policy outlook.
Bonds Commentary
The US 10-year Treasury yield rose to 4.58%, its highest since late May, as escalating Middle East tensions and a nearly 10% two-day surge in oil prices revived inflation concerns. Renewed US-Iran hostilities and attacks near the Strait of Hormuz increased fears of supply disruptions, prompting markets to raise the implied probability of a September Federal Reserve rate hike to around 70% from 58% previously.
Futures Update
US stock futures declined sharply, with S&P 500 and Dow contracts falling more than 1% and Nasdaq 100 futures dropping 1.6%, as renewed US-Iran tensions drove oil prices and Treasury yields higher, intensifying inflation and interest-rate concerns. Banks, industrials and semiconductor stocks weakened, while fears of slower AI infrastructure spending and rising Chinese chip competition pressured Micron, Sandisk and Nvidia. Meta, Amazon and Microsoft also fell ahead of the Federal Reserve’s June meeting minutes.
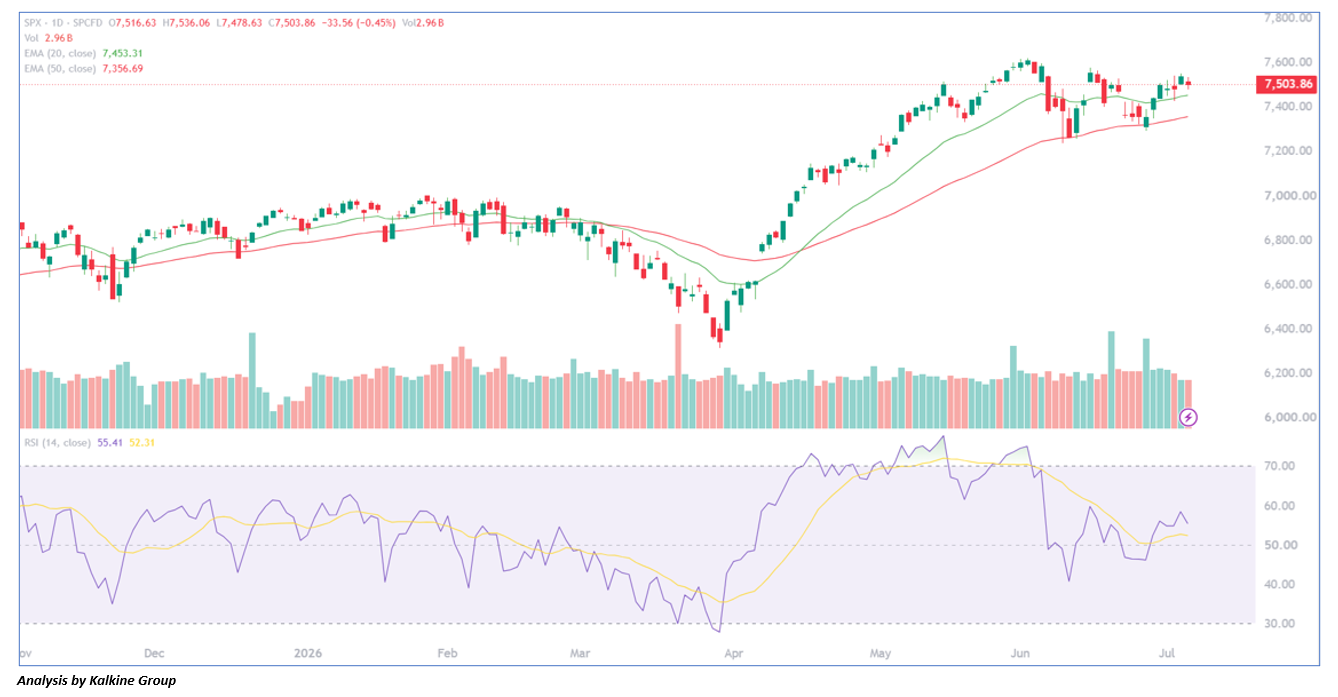
After facing selling pressure early in Tuesday's session, stocks attempted to recover around midday but lost momentum in afternoon trading, with the major averages ending the day lower. The tech-heavy Nasdaq led the declines, reflecting continued weakness in growth stocks. From a technical perspective, the S&P 500 maintains a mildly bearish intraday outlook after failing to hold gains near recent highs. While the index remains above its 20-day and 50-day EMAs, preserving the broader bullish trend, the recent pullback points to near-term profit-taking. Meanwhile, the RSI is hovering around the neutral 50 level, indicating fading momentum. Unless the index reclaims immediate resistance levels, it may remain vulnerable to additional intraday weakness before renewed buying interest emerges.

 Nov 02, 2026

 Please wait processing your request...