
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
Oil Shock Returns: Escalating Middle East tensions have driven crude oil prices sharply higher, reviving inflation concerns.
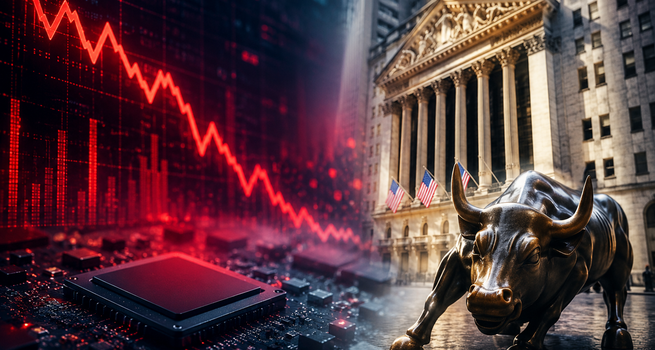
Wall Street Futures Slide: S&P 500, Dow Jones, and Nasdaq futures weakened as investors shifted away from risk assets.
AI Stocks Under Pressure: Semiconductor and AI infrastructure companies extended losses amid concerns over slower hyperscaler spending.
Fed Back in Focus: Higher energy prices may complicate the Federal Reserve's inflation fight ahead of the latest FOMC minutes.
Markets Face a Macro Reset: AInvestors are once again weighing geopolitics, inflation, and earnings expectations simultaneously.
Why the US Stock Market Is Falling Today
For much of this year, Wall Street's dominant narrative revolved around artificial intelligence. Investors willingly overlooked stretched valuations, slowing economic momentum, and elevated interest rates so long as AI spending continued to accelerate. That comfortable narrative has suddenly encountered an older and often more disruptive force: geopolitics.
A sharp deterioration in Middle East tensions has injected a fresh layer of uncertainty into financial markets. Reports of renewed military action involving Iran have prompted investors to rapidly reassess risks surrounding global energy supplies, inflation, and monetary policy. The Strait of Hormuz, one of the world's most strategically important oil shipping routes, has once again become central to global macroeconomic thinking.
Markets rarely fear wars solely because of the conflict itself. They fear what wars do to prices.
That distinction matters.
If energy costs remain elevated for an extended period, the consequences reach far beyond oil producers. Transportation becomes more expensive. Manufacturing costs rise. Consumer spending weakens. Most importantly for financial markets, inflation becomes harder to contain.
That possibility explains Wednesday's broad sell-off across equities.
Higher Oil Prices Are Reviving Inflation Fears
The modern global economy still depends heavily on relatively inexpensive energy.
Whenever geopolitical events threaten oil supply, financial markets immediately begin recalculating future inflation.
Higher crude prices function much like an additional tax on economic activity. Airlines face rising fuel expenses. Logistics companies experience higher transportation costs. Manufacturers absorb increased input prices before eventually passing them to consumers.
Inflation, which had shown signs of gradual moderation over recent months, suddenly appears less predictable.
Bond markets reacted accordingly.
Treasury yields moved higher as investors priced in the possibility that persistent energy inflation could delay any future easing of monetary policy. Rising yields simultaneously increase borrowing costs for households, businesses, and governments while reducing the relative attractiveness of richly valued growth companies.
It represents precisely the combination equity investors dislike most: slowing growth alongside renewed inflationary pressure.
Why the Federal Reserve Has Become Even More Important
The timing of these geopolitical developments is particularly significant.
Investors are preparing for the release of minutes from the Federal Reserve's latest policy meeting, hoping to better understand how policymakers currently view inflation risks.
Before energy prices surged, markets had increasingly believed the Federal Reserve could gradually shift toward a less restrictive stance if inflation continued moderating.
That assumption now looks less certain.
Central bankers cannot directly influence geopolitical events or oil production. They can, however, respond if higher energy prices begin feeding into broader inflation expectations.
The Federal Reserve therefore finds itself facing an increasingly familiar dilemma.
Tight monetary policy helps restrain inflation but risks slowing economic growth further. Easier policy supports activity but could allow inflationary pressures to become entrenched again.
Financial markets dislike uncertainty.
The current environment offers plenty of it.
Why AI Stocks Are Leading the Market Lower
Technology stocks have become particularly vulnerable because their valuations increasingly depend upon expectations of extraordinary future earnings rather than current profitability alone.
Semiconductor manufacturers, AI infrastructure suppliers, cloud computing companies, and hyperscale data centre operators have enjoyed enormous investor enthusiasm throughout the AI investment cycle.
Yet these businesses also require unprecedented levels of capital expenditure.
The investment thesis assumes that technology giants will continue committing hundreds of billions of dollars toward AI infrastructure over many years.
Recent market action suggests investors are beginning to question whether that pace can continue indefinitely.
If higher interest rates persist while economic uncertainty increases, executives may become more cautious regarding future spending commitments.
That possibility explains why leading semiconductor companies experienced another wave of selling.
Investors increasingly worry that the extraordinary AI spending cycle may gradually normalize rather than accelerate indefinitely.
The market is beginning to price that possibility.
The Chip Industry Faces Multiple Headwinds
The semiconductor sector now confronts several pressures simultaneously.
First comes valuation.
Many chip companies entered this period trading at historically elevated multiples following months of AI-driven enthusiasm.
Second comes macroeconomic uncertainty.
Higher oil prices and rising interest rates reduce investor appetite for expensive growth assets.
Third comes intensifying competition.
Reports suggesting that major Chinese technology firms continue expanding domestic semiconductor development reinforce concerns that the global competitive landscape could become significantly more fragmented over time.
While technological leadership remains concentrated among established Western chipmakers, long-term market share assumptions are becoming increasingly contested.
For investors, higher uncertainty almost always translates into lower valuation multiples.
Banks, Industrials and Cyclical Stocks Also Feel the Pressure
The weakness extended well beyond technology.
Banks declined as higher market volatility raised concerns over slower lending activity and softer economic growth.
Industrial companies similarly weakened because rising energy prices directly affect manufacturing costs and global trade.
Transportation businesses remain particularly exposed whenever fuel prices accelerate.
Taken together, these sectors illustrate that the current sell-off is fundamentally macroeconomic rather than company-specific.
Investors are reducing exposure across economically sensitive industries rather than reacting to isolated corporate developments.
Wall Street Is Shifting From Growth to Risk Management
Financial markets often move through distinct psychological phases.
During optimistic periods, investors primarily search for opportunities.
During uncertain periods, they first seek protection.
Current market behaviour increasingly reflects the latter.
Portfolio managers appear less concerned with identifying the next AI winner and more focused on understanding downside risks stemming from geopolitics, inflation, and monetary policy.
This represents a meaningful shift in market leadership.
For much of the previous year, nearly every discussion centred on artificial intelligence.
Now conversations increasingly revolve around oil, inflation, interest rates, and geopolitical uncertainty.
History suggests these transitions can happen remarkably quickly.
What Investors Should Watch Next
Several developments will likely determine whether this sell-off proves temporary or evolves into something more sustained.
First, markets will closely monitor whether energy prices continue climbing or stabilise. Oil has historically been one of the fastest channels through which geopolitical events influence the broader economy.
Second, investors will examine the Federal Reserve's latest communication for clues regarding inflation and interest-rate expectations. Any indication that policymakers are becoming more concerned about energy-driven inflation could further pressure equities.
Third, corporate commentary from major technology companies will become increasingly important. Investors will want reassurance that planned spending on artificial intelligence infrastructure remains intact despite growing macroeconomic uncertainty.
Finally, attention will remain fixed on developments across the Middle East. Financial markets can often absorb geopolitical shocks if they remain contained. A prolonged disruption to energy supplies, however, would present a more complex challenge for both policymakers and investors.
For now, Wall Street finds itself navigating an uncomfortable convergence of risks. Elevated equity valuations, persistent inflation concerns, geopolitical instability, and uncertainty surrounding monetary policy have combined to weaken the confidence that characterised markets only weeks ago.
Whether this represents a temporary correction or the beginning of a broader repricing will depend less on corporate earnings than on the interaction between geopolitics, energy markets, and central-bank policy. In today's market, the price of oil may once again matter as much as the promise of artificial intelligence.

 Nov 02, 2026

 Please wait processing your request...