
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Tuesday as easing pressure from bond yields and fresh AI deals supported technology shares. The S&P 500 gained 0.6% and the Nasdaq 100 rose 0.5% to record highs, while the Dow added 253 points. Constellation Energy surged 12.2% ahead of a nuclear energy agreement with Alphabet, while AMD climbed 2.8% on a strong chip Demand outlook. OpenAI’s talks for USD 30 billion in UAE financing also supported sentiment, alongside gains in Microsoft, Amazon and Nvidia.
Market Movers
Among the top-performing stocks of the session Apimeds Pharmaceuticals US, Inc. surged 55.34%, while Professional Diversity Network, Inc. rallied 48.71%. On the losing side, Armada Acquisition Corp. II. fell 50.32%, while ArriVent BioPharma, Inc. declined 46.98%, making them the weakest performers during the trading day.
Commodities Update
Crude oil rose toward USD 90 per barrel and Brent climbed above USD 101 on Wednesday as renewed attacks on tankers in the Strait of Hormuz and Houthi missile activity heightened concerns over Middle East energy flows. However, prices remained lower for the week as Persian Gulf shipments showed signs of recovery and Saudi Arabia restored its East-West pipeline capacity to 5.8 million barrels per day. US industry data also showed a 2.1-million-barrel decline in crude inventories, with official figures due later in the day.
Gold fell below USD 4,150 an ounce and silver dropped below USD 61 on Wednesday as rebounding oil prices amid Middle East tensions renewed Inflation and rate hike concerns. Treasury yields near multi-decade highs also pressured precious metals, reflecting persistent inflation, fiscal risks and rising AI-related Debt issuance. Despite these concerns, weaker US jobs data supported nearly an 80% probability of the Fed holding rates unchanged this month, with investors awaiting its latest meeting minutes for policy guidance.
Macro Updates
US Mortgage Applications Fall as Rates Reach Near Three-Year High
US mortgage applications fell 4.2% in the week ended October 2, marking a fifth consecutive decline and reaching their lowest level since January 2025. The average 30-year fixed mortgage rate rose 19 basis points to 7.49%, its highest since November 2023 and seventh straight weekly increase, as elevated Treasury yields, energy-driven inflation and expectations of further Fed tightening pushed borrowing costs higher. Refinancing applications dropped 7.5%, while purchase applications declined 2.1%.
Dollar Hits Highest Level Since March 2025
The dollar index rose above 102 on Wednesday as higher oil prices renewed inflation concerns and expectations of tighter Fed policy for longer. Investors awaited FOMC minutes following last month’s 25-basis-point hike, with markets pricing in a 78% chance of unchanged rates this month and a 69% probability of a December hike. The dollar gained most against the euro, which faced pressure from political and fiscal concerns in Spain and France.
US Crude and Gasoline Inventories Decline
US crude inventories fell by 2.09 million barrels in the week ended October 2, while gasoline stocks declined by 1.37 million barrels. Cushing and distillate inventories rose by 866,000 and 461,000 barrels, respectively. Oil production increased to 13.955 million barrels per day in the week ended September 25, while an additional 800,000-barrel SPR release reduced reserves to 283 million barrels.
Bonds Commentary
The US 10-year Treasury Yield rose to 5.32% on Wednesday, revisiting levels last seen in 2002, while the 30-year yield reached a fresh 24-year high of 5.70%. Rebounding oil prices renewed concerns over inflation and tighter Fed policy, with investors awaiting FOMC minutes for guidance. A USD 39 billion 10-year note auction on Wednesday and a 30-year bond auction on Thursday will test demand for US government debt.
Futures Update
US Equity futures retreated from record highs as rising bond yields fuelled concerns over borrowing costs and economic growth. S&P 500, Nasdaq and Dow futures fell 0.5%, 0.8% and 0.7%, respectively, while Iranian attacks in the Strait of Hormuz heightened shipping costs and energy inflation risks. AI infrastructure stocks weakened despite plans for SpaceX to issue USD 40 billion in debt to purchase Nvidia chips, while pharmaceutical and consumer staples stocks advanced.
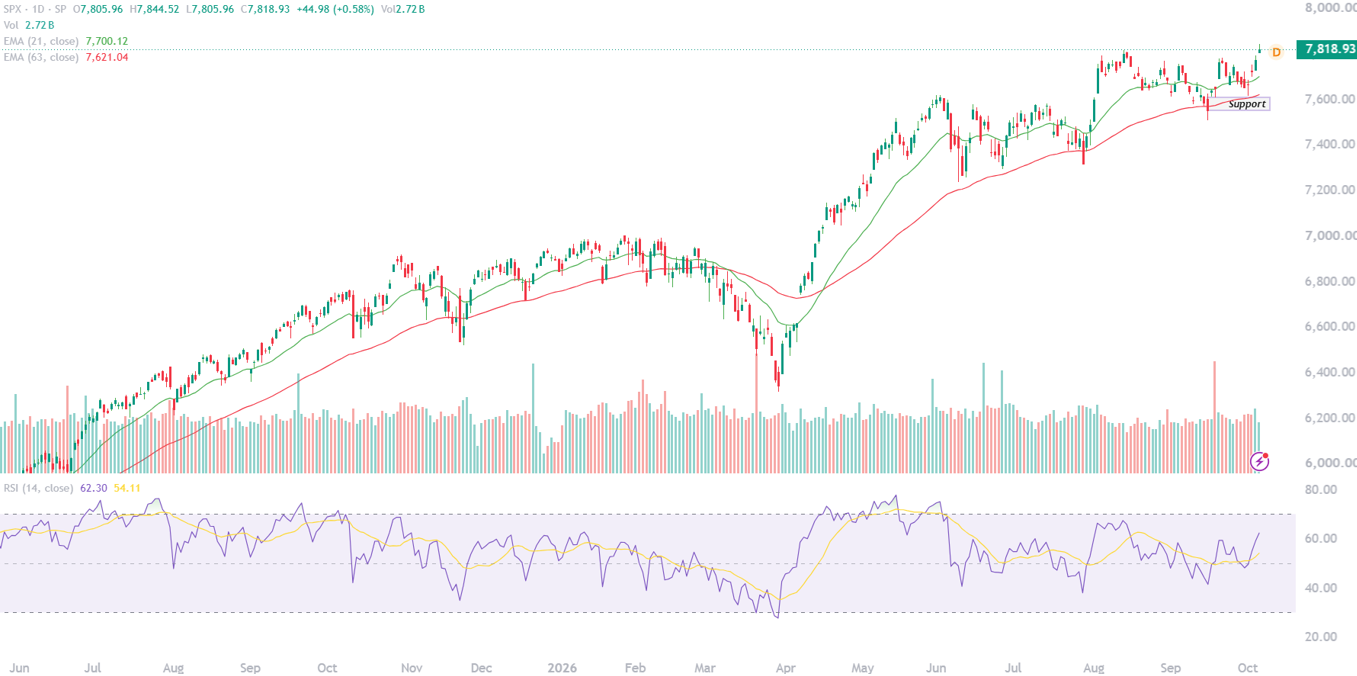
Stocks showed a notable move higher early in Tuesday's session, then gave back some ground through the day but still turned in a strong performance. The major averages extended their recent uptrend, with the Nasdaq and S&P 500 both reaching new record closing highs. On the daily chart, the S&P 500 (SPX) opened at 7,805.96, traded between 7,805.96 and 7,844.52, and closed at 7,818.93 (+0.58%). The candle surrendered part of its gains, and the prominent upper wick shows sellers faded the push toward 7,844, which is the main clue for a bearish intraday view. Price is extended above the 21 EMA at 7,700.12 and the 63 EMA at 7,621.04, and RSI at 62.3 has climbed quickly toward the 70 line, so a short-term pullback to relieve that stretch is plausible. Resistance at 7,844.52, and a failure to hold above 7,805 , would be the first sign that sellers are taking control. Downside targets are the 7,750 area, then the 21 EMA near 7,700, with the 63 EMA and the marked support box around 7,620 as the major level. Volume is moderate at 2.72B, so there is no strong breakout confirmation to prevent a reversal, and a sustained move back above 7,845 would invalidate the bearish idea. Because the broader trend remains bullish, this would be a counter-trend, short-term view.

 Nov 17, 2026
 Please wait processing your request...