
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks recovered from earlier losses on Thursday, with the S&P 500 gaining 0.3%, the Nasdaq ending near flat and the Dow rising 557 points. AI-related stocks stabilised after Nvidia CEO Jensen Huang dismissed suggestions that CoreWeave would need a bailout, helping its shares climb 5.9%. Microsoft and Oracle gained 1.1% and 3%, respectively, while chipmakers ended mixed. A Treasury rally also supported sentiment, although concerns persisted over heavy borrowing and circular financing within AI infrastructure.
Market Movers
Among the top-performing stocks of the session Better Home & Finance Holding Company. surged 32.51%, while Indaptus Therapeutics, Inc. rallied 28.96%. On the losing side, SciSparc Ltd. fell 44.90%, while FMC Corporation. declined 30.53%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded around USD 98 per barrel on Friday, gaining more than 6% for the week, while Brent rose above USD 103 as Middle East tensions and Supply disruptions outweighed planned emergency reserve releases. Supply concerns intensified after the Iranian-struck GFS Pride sank in the Strait of Hormuz, although more than 40 vessels transited the waterway over the previous 24 hours. Meanwhile, IEA members pledged to release the remaining 100 million barrels under their emergency intervention, while Washington reportedly considered easing sanctions on selected vessels carrying Iranian, Russian or Venezuelan oil.
Gold climbed toward USD 4,200 an ounce and silver rose above USD 57 on Friday as an Equity selloff and heightened Middle East tensions boosted safe-haven demand. Falling bond yields supported both metals, while escalating Saudi–Houthi hostilities and the sinking of a container ship in the Strait of Hormuz heightened geopolitical concerns. Meanwhile, stronger-than-expected US economic data reinforced expectations of tighter monetary policy, with markets pricing in a 72% probability of unchanged Fed rates this month and a 92% likelihood of a December rate hike.
Macro Updates
US Trade Prices Accelerate Above Expectations in September
US export prices rose 2.2% in September, exceeding expectations of 1% and marking their strongest monthly increase since April, as agricultural and nonagricultural prices climbed 2.6% and 2.1%, respectively. Annual export price growth reached 11.6%, the highest since July 2022. Import prices increased 1.1% month-on-month, surpassing forecasts of 0.8%, driven by a 4.8% surge in fuel costs and a 0.7% rise in non-fuel prices. Import prices, which exclude tariffs, advanced 8.1% annually, highlighting broad-based external price pressures.
Dollar Heads for Weekly Decline as Bond Yields Fall
The dollar index fell to a two-week low of 101.6 on Friday, declining around 0.4% for the week and ending three consecutive weekly gains. Concerns over AI spending amid high interest rates weighed on equities, bond yields and the dollar. Despite stronger-than-expected CPI and PPI readings, markets priced in an 85% probability of unchanged rates in October and nearly a 77% chance of a 25-basis-point hike in December. Fed Chair Warsh’s comments reinforced expectations of an October pause, while offering no clear signal on further tightening.
Warsh’s Remarks Temper Expectations of an October Rate Hike
Fed Chair Warsh avoided signalling the outcome of October’s FOMC meeting, stating that stronger-than-expected Inflation had not changed his economic assessment, prompting traders to reduce expectations of an immediate rate hike. However, he reiterated concerns about persistently elevated price pressures. The Fed raised rates by 25 basis points to 3.75%–4.00% in September, its first increase since 2023, with all 19 policymakers supporting the move and a majority projecting another hike before year-end.
Bonds Commentary
The US 10-year Treasury Yield edged up to 5.11% on Friday after falling 11 basis points in the previous session, but remained around 14 basis points lower for the week as a retreat from AI-related stocks supported safe-haven demand. Despite hotter-than-expected CPI and PPI readings, Fed Chair Warsh’s comments reinforced expectations of unchanged rates this month. Markets priced in an 85% probability of an October hold and nearly a 77% chance of a 25-basis-point hike in December.
Futures Update
US stock futures were broadly flat on Friday but headed for sharp weekly losses as concerns over AI Investment returns, Credit risks and potential Fed rate hikes weighed on sentiment. CoreWeave fell nearly 5% premarket, extending its weekly decline to 15%, while Micron, AMD and Marvell lost up to 2.5%. Strong inflation data added pressure on technology stocks. Meanwhile, Tesla gained 3% and SpaceX rose 1.5% after Tesla unveiled a Roadster featuring SpaceX thrusters, fuelling Merger speculation.
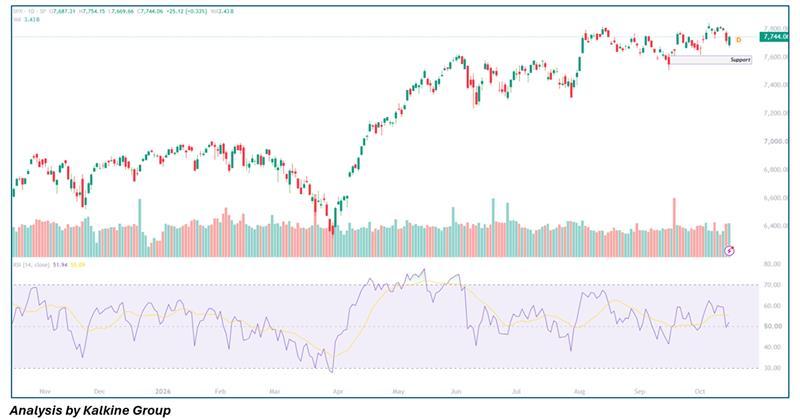
Stocks extended Wednesday’s slump early on Thursday but reversed course through the session, with all major averages finishing higher and the Dow posting its best close in a month. The S&P 500 (SPX) looks neutral to mildly bullish, closing at 7,744.06 (+0.33%) after rebounding from a low of 7,669.66, which shows buyers defending dips. It is consolidating below resistance at 7,800-7,830, with support at 7,600-7,650. The RSI at 51.94 sits on the midline, so momentum is flat, and average Volume (3.43B) suggests little conviction either way. A move above 7,754 targets 7,800-7,830, while a break below 7,670 brings support back into play. Expect choppy, range-bound action until then, though the broader uptrend favors buying dips.

 Nov 02, 2026

 Please wait processing your request...