
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indices closed higher on Monday, led by strong semiconductor gains, with the S&P 500 rising 0.7%, the Nasdaq 100 advancing 1.3%, and the Dow reaching a record 53,056. Broadcom, AMD, Intel, Micron, and Nvidia gained amid continued optimism over AI demand and upcoming industry updates, although concerns over competition, excess capacity, and AI investment returns persisted. Meanwhile, US services activity expanded at a slower pace in June, while investors awaited the Federal Reserve’s meeting minutes for guidance on inflation and labour-market risks.
Market Movers
Among the top-performing stocks of the session Lianhe Sowell International Group Ltd. surged 277.78%, while UTime Limited. rallied 171.53%. On the losing side, Julong Holding Limited. fell 49.66%, while. Dreamland Limited declined 25.52%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose above USD 69 per barrel and Brent approached USD 73 on Tuesday after attacks on commercial shipping near the Strait of Hormuz revived concerns over potential supply disruptions and the durability of the US-Iran agreement. However, prices remained near late-February lows as stronger supply expectations and softer market conditions limited gains. Eight Japan-linked vessels reportedly exited the strait, while Saudi Aramco cut the August price of Arab Light crude for Asian buyers by USD 11 per barrel to a USD 1.50 discount to the regional benchmark.
Gold eased below USD 4,150 per ounce and silver slipped under USD 62 on Tuesday, while retaining most of the previous week’s gains as investors awaited the Federal Reserve’s June meeting minutes for clearer interest-rate guidance. Softer US employment data and downward payroll revisions reduced expectations of a near-term rate hike, with markets assigning about a 50% probability to a September increase. Precious metals were also supported by lower oil prices, recovering traffic through the Strait of Hormuz, higher Middle Eastern output, price cuts by regional producers, and an OPEC+ production increase for next month.
Macro Updates
US Logistics Activity Reaches Four-Year High
The US Logistics Manager’s Index rose to 71.1 in June 2026 from 69.5 in May, marking the strongest sector expansion since March 2022. Growth was driven by a sharp increase in inventory levels to 60.5 as large companies and downstream retailers built stocks ahead of the second-half peak season and potential tariff increases. This lifted warehousing and transportation utilization and pushed warehousing prices higher, while warehousing capacity fell into contraction at 47.5 as storage demand intensified.
Dollar Remains Pressured by Softer Rate Expectations
The US dollar index remained below 101 on Tuesday as weaker June employment data and downward payroll revisions reduced expectations of further Federal Reserve rate hikes. Markets now assign about a 50% probability to a September increase, down from roughly two-thirds before the jobs report. Investors are awaiting the Fed’s June meeting minutes and US trade deficit data for further policy signals, while the dollar weakened against most major currencies but stayed near four-decade highs against the Japanese yen.
Bonds Commentary
The US 10-year Treasury yield rose to 4.50% on Tuesday, its highest level in two weeks, as higher oil prices revived inflation concerns following an attack on an LNG carrier near the Strait of Hormuz. The incident highlighted ongoing Middle East supply risks and pushed expectations of a September Federal Reserve rate hike to about 58% from 56%. Investors now await the FOMC minutes for further guidance after the Fed’s more hawkish June stance.
Futures Update
US stock futures edged lower on Tuesday after Wall Street began the week with solid gains, including a record Dow close above 53,000. The S&P 500 and Nasdaq also advanced, supported by strong technology shares such as Tesla, AMD, Meta, Broadcom, and Western Digital. In after-hours trading, Rivian fell more than 9% following a 75-million-share public offering, while Samsung Electronics declined in South Korean pre-market trade despite stronger-than-expected profits driven by AI data-centre memory demand.
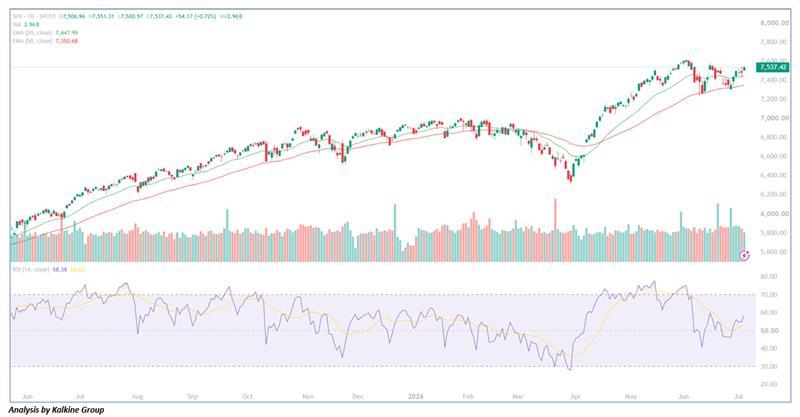
Following the extended Independence Day weekend, U.S. stocks traded mostly higher on Monday as investors returned with renewed buying interest. The S&P 500 continues to maintain a constructive short-term technical setup, trading comfortably above both the 20-day and 50-day EMAs, which are providing strong dynamic support. Momentum is also improving, with the RSI recovering to around 58, suggesting strengthening buying interest while remaining below overbought levels. As long as the index holds above the 7,500–7,520 support zone, the bullish bias is expected to remain intact, with an intraday upside target in the 7,580–7,620 range. A decisive move above 7,560 could attract additional buying momentum, while a break below 7,500 may trigger mild profit-taking toward the 20-day EMA.

 Nov 16, 2026
 Please wait processing your request...