
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indices closed lower on Friday as weakness in chipmakers and hawkish remarks from Federal Reserve Chair Kevin Warsh increased expectations of a September rate hike. The S&P 500 fell 0.2%, the Nasdaq declined 0.7% and the Dow edged lower. Marvell, Nvidia, AMD and Broadcom retreated, while Alphabet, Microsoft, Amazon and Meta advanced. Industrial and pharmaceutical stocks also weakened amid renewed Inflation and monetary-policy concerns.
Market Movers
Among the top-performing stocks of the session Bleichroeder Acquisition Corp. II. surged 95.20%, while Swvl Holdings Corp. rallied 41.18%. On the losing side, Wetour Robotics Limited. fell 50.26%, while Vistance Networks, Inc. declined 47.89%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices surged more than 3% on Monday, with WTI exceeding USD 86 per barrel and Brent topping USD 91, as renewed US-Iran strikes and reports of Mining activity intensified concerns over shipping through the Strait of Hormuz. Although the reported tanker incident remains unverified, fears of further Supply disruption supported prices. WTI and Brent gained about 2% and 3.5%, respectively, in August after sharp July increases, while an estimated 6–8 million barrels per day continue to transit the waterway.
Gold fell below USD 4,450 per ounce, while silver traded near USD 66.4 after declining more than 4% in the previous session, as hawkish comments from Federal Reserve Chair Kevin Warsh raised expectations of a September rate hike. Markets now assign a 57% probability to a 25-basis-point increase, up from around 40% a week earlier, while rising oil prices added inflationary pressure. Despite the pullback, gold and silver remain on track to gain more than 10% and 15%, respectively, in August.
Macro Updates
Dollar Pauses as Rate-Hike Expectations Rise
The US Dollar index edged down to 99.5 on Monday following a three-session rally to a two-week high, as markets assessed a roughly 60% probability of a 25-basis-point Federal Reserve rate hike in September. Fed Chair Kevin Warsh’s hawkish inflation remarks supported the dollar, although uncertainty over the timing of policy tightening persisted. Investors now await key economic releases, including Friday’s employment report, while the index remains on track for a 0.2% decline in August.
Bonds Commentary
The 10-year US Treasury Yield traded near 4.7% on Monday after three consecutive sessions of gains, as Federal Reserve Chair Kevin Warsh’s hawkish inflation remarks raised the probability of a 25-basis-point September rate hike to around 57% from 40% a week earlier. An upward revision to US consumer sentiment further supported yields, while investors awaited Friday’s August employment report for additional guidance on the monetary-policy outlook.
Futures Update
US Equity futures traded mostly lower on Monday as rising oil prices reinforced inflation concerns and expectations of a potential Federal Reserve rate hike. S&P 500 and Nasdaq 100 futures fell as much as 0.5%, while Dow futures were marginally lower. Renewed US-Iran strikes and continued disruption to Persian Gulf exports lifted Treasury yields and pressured rate-sensitive stocks, with Microsoft, Palantir, Alphabet, Tesla, JPMorgan and Visa declining in premarket trading.
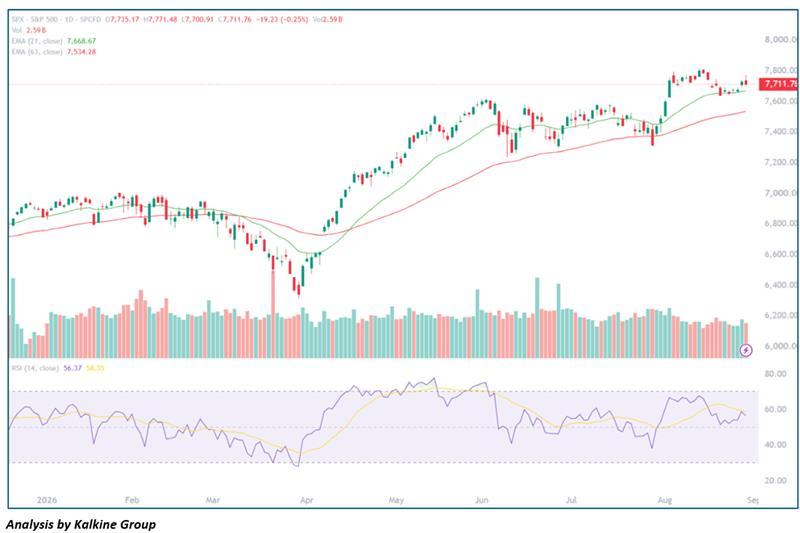
The S&P 500 remains mildly bullish as the index trades around 7,711.76, holding above the 21-day EMA at 7,668.67 and 63-day EMA at 7,534.28, indicating that the broader trend remains positive. However, price action is showing consolidation near the 7,700–7,750 zone, while the RSI at 56.37 remains in neutral territory and below its RSI average of 58.35, suggesting that upside momentum is currently moderate. A sustained move above 7,750–7,780 could open the way toward the recent high near 7,800, whereas a break below 7,700 may trigger a pullback toward 7,670, with further support near 7,630–7,600. Overall, the intraday bias remains neutral to mildly bullish, with buying interest likely to persist as long as the index holds above the 7,670 support zone.

 Nov 16, 2026
 Please wait processing your request...