
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Tuesday as elevated bond yields, rising energy prices and Inflation concerns pressured markets. The S&P 500 fell 0.7%, the Nasdaq 100 declined 1.7% and the Dow lost 116 points, led by sharp losses in AI-linked chipmakers including Nvidia, Broadcom, Micron, AMD and Intel. Financial stocks also weakened, while Home Depot slipped despite reporting better-than-expected earnings.
Market Movers
Among the top-performing stocks of the session Profusa, Inc. surged 506.62%, while FreeCast, Inc. rallied 144.24%. On the losing side, SunScout Holding Limited. fell 32.33%, while Recon Technology, Ltd. declined 25.45%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices extended gains for a fourth straight session on Wednesday, with WTI approaching $86 per barrel and Brent nearing $92, as stalled US-Iran diplomacy, the continued US naval blockade and vessel attacks kept Strait of Hormuz Supply risks elevated. Prices also received support from a 328,000-barrel decline in US crude inventories last week.
Gold traded near $4,350 an ounce and silver fell toward $63 on Wednesday as elevated Global Bond yields, fiscal concerns and persistent inflationary pressures weighed on precious metals. Rising oil prices and continued US-Iran tensions added pressure, while investors awaited the Federal Reserve’s July meeting minutes and Chair Kevin Warsh’s Jackson Hole remarks for Monetary Policy signals.
Macro Updates
US Mortgage Applications Edge Lower as High Rates Weigh on Demand
US mortgage applications declined 0.4% in the second week of August as the average 30-year fixed mortgage rate remained elevated at 6.77%. Purchase applications fell 2% amid affordability concerns and economic uncertainty, while refinancing Demand increased about 2% but remained subdued due to persistently high borrowing costs.
US Dollar Weakens Ahead of Fed Minutes
The dollar index fell to around 99.5 as investors awaited the Federal Reserve’s July meeting minutes for monetary policy signals. Weak US economic data has strengthened expectations that rates will remain unchanged in September, while prospects of another hike this year have diminished despite elevated global bond yields.
US Crude Inventories Post First Decline in Five Weeks
US crude inventories fell by 328,000 barrels in the week ended August 14, marking their first decline in five weeks, while Cushing stocks dropped by 1.44 million barrels. Crude production remained near a record 13.81 million barrels per day, gasoline inventories rose by 1.08 million barrels and distillate stocks declined by 2.80 million barrels. Meanwhile, the Strategic Petroleum Reserve fell by another 5.3 million barrels to 293.4 million.
US Pending Home Sales Decline for Second Month
US pending home sales fell 2.3% month over month in July 2026, missing expectations for a 0.3% increase, as contract signings declined across all four major regions. Sales were also down 2.2% from a year earlier, with elevated mortgage rates and record home prices continuing to constrain housing demand.
Bonds Commentary
The 10-year US Treasury Yield eased below 4.7% on Wednesday as investors awaited the Federal Reserve’s July meeting minutes for monetary policy signals. However, persistent inflation concerns, rising government and corporate Debt issuance, widening fiscal deficits and expectations of significant AI-related borrowing continued to support elevated long-term yields and higher term premiums.
Futures Update
US Equity futures were mixed on Wednesday as elevated bond yields and energy prices weighed on sentiment. S&P 500 and Dow futures were flat, while Nasdaq 100 futures declined 0.5% amid weakness in major technology stocks. Retailers fell following quarterly results, while Analog Materials gained on strong guidance and Moderna and Merck surged on positive melanoma Vaccine trial data. Investors awaited the FOMC minutes for interest-rate signals.
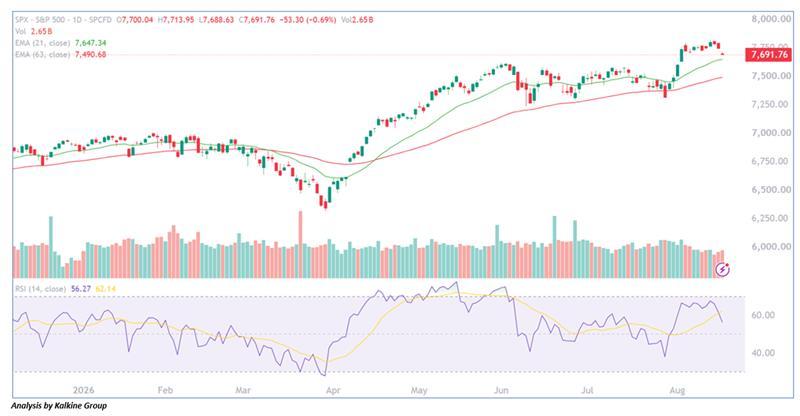
Stocks moved mostly lower during Tuesday’s session, extending the pullback seen over the previous two trading days, with the Nasdaq underperforming amid renewed weakness in technology stocks and all three major averages ending in negative territory. The S&P 500 retains a mildly bullish intraday bias despite its recent retreat from record highs, closing at 7,691.76 while holding above the 21-day EMA at 7,647.34 and 50-day EMA at 7,490.68, keeping the broader uptrend intact. However, the decline in price and RSI at 56.27 indicate that short-term momentum has cooled, suggesting the possibility of further consolidation. The 7,650–7,620 zone remains a key support area, and holding above this region could encourage a rebound toward 7,750–7,800, followed by 7,850–7,900. Conversely, a sustained break below 7,620 could weaken the near-term outlook and expose the index to support around 7,550–7,500. Overall, the broader trend remains constructive, although continued weakness in technology and semiconductor stocks, along with elevated Treasury yields, could keep near-term upside momentum in check.

 Nov 02, 2026

 Please wait processing your request...